| DARK MAJESTIC | Financial leaders' speeches
September 2026 | | THE MONTH IN THREE POINTS AI at the centre, Europe's capital markets push, and shocks that pull prices both ways September was dense: 36 speeches by the heads of 21 institutions. Three threads ran through most of them. | 1 | AI becomes an economic question The BIS, the ECB, the Reserve Bank of India and the Bank of Korea treated artificial intelligence as a matter for central banks, not only for tech firms: how to measure it, how its huge investment is financed, and what it changes for bank risk. India went furthest, with concrete demands on vendor contracts, audits and stress tests. | | 2 | Europe makes the case for integration ESMA's chair spoke four times about the market integration package, which she presented as possibly the largest EU market reform since the post-crisis years. The ECB, the Bundesbank and the new Banque de France Governor argued that pooling savings, simpler rules and truly European banks are Europe's answer to fading growth drivers. | | 3 | Tariffs, conflict and energy pull prices both ways The Bank of Canada, the Reserve Bank of Australia and the ECB explained how US tariffs, the Middle East conflict and energy prices can push inflation up while slowing growth. The ECB set out how it reads such a shock: it reacts to the risk of inflation becoming embedded, not to energy prices themselves. |
READ FIRST - Artificial intelligence, growth and financial stability: challenges for central banks — Pablo Hernández de Cos, Bank for International Settlements
- The choice facing Europeans — Christine Lagarde, European Central Bank
- Strong and modern supervision in a fast-moving world — Erik Thedéen, Basel Committee on Banking Supervision
|
| SPEECHES 36 | INSTITUTIONS 21 | TOP TOPIC Technology, AI and cyber risk |
| | MOST ACTIVE INSTITUTIONS | SPEECHES | | European Securities and Markets Authority | 4 | | European Central Bank | 4 | | Deutsche Bundesbank | 3 | | Bank Negara Malaysia | 2 | | Bank of Canada | 2 |
| | TOP TOPICS | SPEECHES | | Technology, AI and cyber risk | 15 | | Growth, investment and productivity | 14 | | Development and emerging economies | 12 | | Financial stability | 11 | | Climate, energy and nature | 11 |
|
| 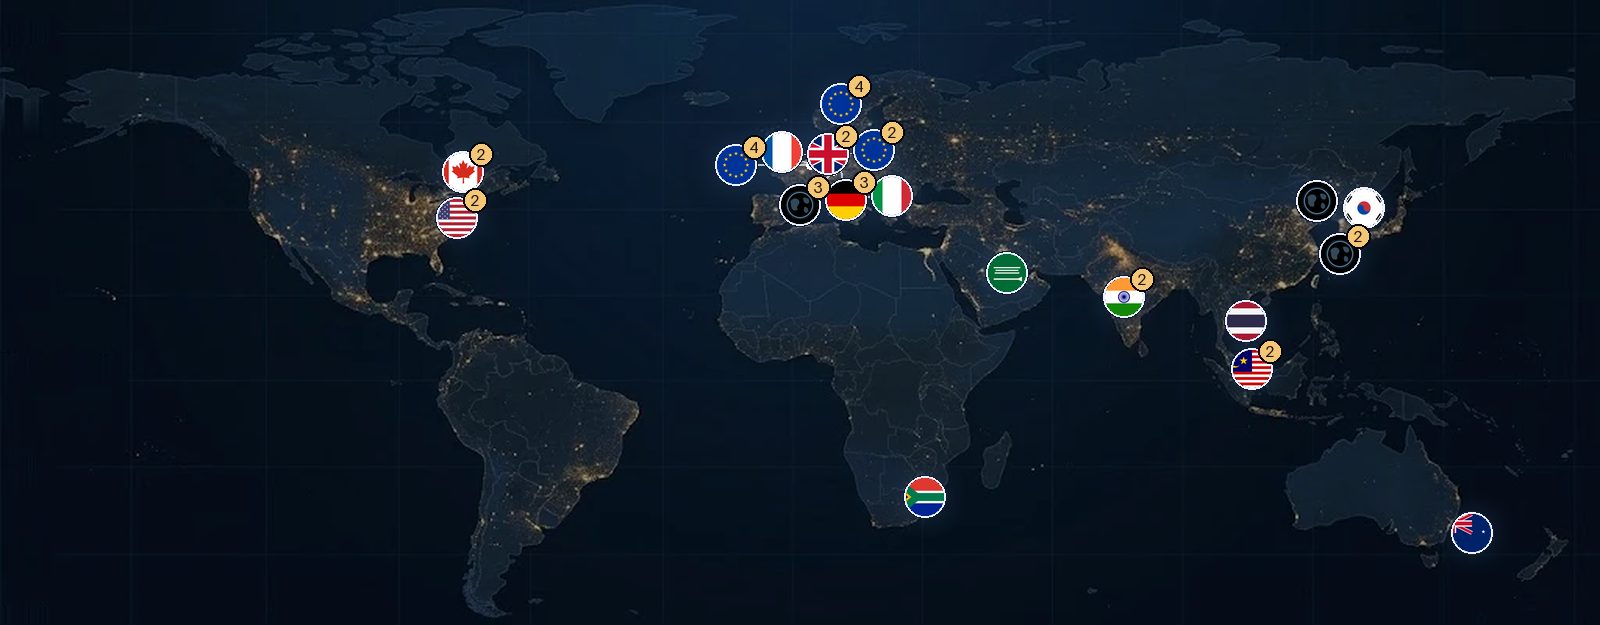 Where the 21 institutions that spoke this month are based (17 cities); the bigger the dot, the more speeches. Map image generated by AI. | | ALL SPEECHES OF THE MONTH, NEWEST FIRST | Basel Committee on Banking Supervision Wiki30 September 2026 · Erik ThedéenWiki (Chair) Strong and modern supervision in a fast-moving world Monetary policy and interest rates · Financial stability · Banking regulation and supervision · Technology, AI and cyber risk CONTEXT Opening address to the 24th International Conference of Banking Supervisors, hosted by Bank Indonesia; the Basel Committee sets global bank standards and must keep supervision effective as risks change quickly. WHY IT MATTERS Shifts the Basel Committee's emphasis from post-crisis capital rules towards supervision quality, governance and risk management. PROBLEMS RAISED | 1. | Weak governance and business models can hide behind satisfactory ratios. | | 2. | Supervisors must keep pace with fast-moving technology and risks. | | 3. | Qualitative weaknesses eventually become quantitative shocks. |
| SOLUTIONS PROPOSED | 1. | See, say and act: spot shortcomings promptly and use the available toolkit. | | 2. | Keep modernising supervision with better tools and skills. | | 3. | Maintain the resilience gained from Basel III while focusing on governance and risk management. |
|
FULL SUMMARY 1. The challenge Opening the 24th ICBS, the worldwide gathering of bank supervisors held this year in Bali with Bank Indonesia and the Indonesian financial regulator as hosts, Basel Committee Chair Erik Thedéen asked how supervisors can stay effective amid fast change: AI, cyber threats, new forms of intermediation, geopolitical tension and political pressure on independent authorities. His answer is that supervision must be both strong and modern. Critics often treat the first as rigid and hostile to innovation and the second as a polite word for leniency; he sees the two as complementary, and draws a parallel with Indonesia's history as a trading crossroads that prospered by adapting to change while keeping its footing. 2. Rules are not enough He recalls what the post-2008 Basel III reforms achieved: core capital ratios of large banks up by over 40% since 2011 to about 14%, the ratio of debt to loss-absorbing capital roughly halved from 30 to 17 times, and liquid assets above a fifth of balance sheets, which helped banks survive the pandemic, rapid rate rises and the 2023 turmoil. He notes in passing that the public searches far more for Basel's rules than for its supervisory principles, and urges full, consistent and timely implementation of the remaining standards. But many failed banks, from Northern Rock to Silicon Valley Bank, met their minimum ratios before collapsing. Weak governance, poor rate-risk management and unstable funding were the real problems. Those hidden weaknesses later turned into losses and runs. A ratio only shows a bank's position on one day; supervision has to follow how it got there, where it is heading and how it would react to a change in conditions. Meeting minimum requirements, he stresses, does not mean the absence of risk, which usually shows up first in incentives, behaviour and concentrations, and the Committee's mandate covers supervision and bank practices as much as rules. 3. What effective supervision means He defines it as spotting risks early, telling banks clearly what must change, and acting if they do not, all in good time, since an unresolved finding is unfinished work. Acting is hardest: supervisors need judgment to intervene before risks materialise, anchored in mandate, evidence and due process, avoiding both arbitrariness and box-ticking inertia. Because successes are invisible while failures are spectacular, supervision is accused of laxity after crises and of overreach between them; doing the job therefore takes resolve. Past failures show that warning signs were usually visible but not connected or acted upon in time. He defends judgment as a structured, evidence-based assessment that should be challenged internally, documented and reviewed afterwards, since rules alone cannot capture the specific weaknesses of each bank. 4. Capacity and modernisation Staff, skills, data tools, legal powers, independence, culture and time are, for him, policy matters, and international assessments keep finding shortages of independence, resources and specialists. Tomorrow's supervisors will still need classic prudential knowledge but also expertise in technology, cloud, cyber, data, AI, links with non-banks and geopolitics, combining financial, technological and behavioural expertise in multidisciplinary teams, because a cyber incident can quickly become a liquidity problem and a concentrated business model can unravel when news spreads online. Modernisation should give supervisors more time to think, not just more data to process, and make supervision more forward-looking, data-driven and fast without becoming speculative or careless. Authorities compete with industry for scarce talent, yet underinvestment costs more. AI brings new risks in data quality, models, explainability and dependence on a few providers, addressed in the Committee's new third-party risk principles; small banks, most reliant on outside AI tools, must still keep responsibility in-house. 5. Commitments and cooperation He proposes three commitments: protect mandates, independence, resources and early-intervention powers before a crisis; give staff expertise, time and backing to challenge bank leaders; and build trust by explaining how decisions are taken and evaluated, without hiding behind confidentiality. Finally, he presents international cooperation, as at the conference first held in 1979, as a form of capacity in itself, warning that fragmented supervision would breed fragmented finance and regulatory arbitrage. |
| Bank Negara Malaysia Wiki29 September 2026 · Abdul Rasheed Ghaffour (Governor) Special remarks - JC3 Journey to Zero Conference 2026 Financial stability · Climate, energy and nature · Technology, AI and cyber risk CONTEXT Remarks at the Joint Committee on Climate Change conference in Kuala Lumpur, with awards for green finance projects; Bank Negara Malaysia safeguards stability and is guiding banks through the low-carbon transition. WHY IT MATTERS Calls for financing climate adaptation before disasters strike and for better climate data so banks can price risk. PROBLEMS RAISED | 1. | Climate and nature risks threaten the economy, and floods or landslides arrive before funding does. | | 2. | Rising data-centre demand strains the electricity supply. | | 3. | Climate data is thin, so uncertainty is hard to turn into measurable risk. |
| SOLUTIONS PROPOSED | 1. | Finance adaptation and resilience before the next disaster. | | 2. | Develop a pipeline of projects with risk-sharing structures and room for institutions to take responsible risks. | | 3. | Improve climate data availability and build capacity on nature-related risks. |
|
FULL SUMMARY 1. Climate resilience as a financial issue Closing the 2026 conference of Malaysia's Joint Committee on Climate Change, Bank Negara Malaysia Governor Abdul Rasheed Ghaffour argued that resilience to climate and nature risks is an economic and therefore financial priority, and offered three reflections. 2. Financing a credible energy transition Renewables reached 31% of installed capacity in 2025, up from 25% in 2023, in line with the national roadmap, but AI and data centres, expected to use close to a third of electricity by 2035, will push demand sharply higher. Money exists; the bottleneck is turning it into bankable projects. His example: a remote town in Sabah running on a diesel generator next to a palm-oil mill whose methane could power it. Alone, such a project looks too small and unusual to finance, but with over 120 mills in the state it could become a model adding hundreds of megawatts. A climate finance platform has gathered 45 projects that together ask for over RM5 billion of funding, and he urges financiers to help them scale, and the central bank is studying how rules could give lenders room for well-managed, higher-risk transition financing. 3. Adaptation and nature He wants money spent on resilience before floods or droughts rather than on repairs afterwards, supported by new national climate policies and better, more usable climate data so that uncertainty becomes priced risk. He also asks finance to value nature, on which over half of Malaysia's GDP depends, citing Singapore's choice to turn a concrete canal into a natural river park at half the cost. Banks can start assessing nature risks with existing resources, and he closes by calling for bolder capital, innovation and collaboration. |
| Bank Negara Malaysia Wiki29 September 2026 · Abdul Rasheed Ghaffour (Governor) Welcoming address - 30th anniversary of FAST Development and emerging economies · Technology, AI and cyber risk CONTEXT Welcoming address of Abdul Rasheed Ghaffour, Governor of the Central Bank of Malaysia (Bank Negara Malaysia), delivered by Marzunisham Omar, Deputy Governor, at the Industry Appreciation Dinner commemorating the 30th anniversary of FAST, Kuala…. WHY IT MATTERS Looks at how Malaysia's bond-market infrastructure must evolve with analytics and AI as it celebrates three decades of operation. PROBLEMS RAISED | 1. | Markets evolve, so infrastructure built for the past will not fit the next thirty years. | | 2. | Infrastructure that only processes transactions limits better decision-making. | | 3. | Risk monitoring must keep up with a more sophisticated market. |
| SOLUTIONS PROPOSED | 1. | Evolve the infrastructure alongside the market. | | 2. | Use analytics and AI to deliver richer insights and transparency. | | 3. | Strengthen risk monitoring through the next-generation FAST+ platform. |
|
FULL SUMMARY 1. Thirty years of an invisible backbone Marking 30 years of FAST, the electronic system Bank Negara Malaysia uses to issue and auction debt and money-market securities, Governor Abdul Rasheed Ghaffour recalled that it replaced a paper process and became a pillar of the local bond and sukuk market. He argued that market infrastructure, though unseen, is what lets savings reach productive investment. 2. What it made possible The market has grown to about RM2.35 trillion by mid-2026, among the region's largest in local currency, and companies raised over RM377 billion through bonds between January 2025 and June 2026. Sukuk now make up more than 60% of the market, with over RM1.4 trillion outstanding, and Malaysia issued the first sustainable and responsible investment sukuk in 2015 and the first green sukuk in 2017. The system also kept markets working through stress and the pandemic. 3. The next generation Because AI, investor expectations and interconnected markets are changing finance, the central bank is building FAST+, meant to be smarter (analytics and risk monitoring), better linked across issuers, investors and regulators, and open to tokenised and programmable instruments without sacrificing safety. With a new securities depository system soft-launched on 25 September 2026, it will support issuing, settling and holding tokenised bonds and sukuk. |
| European Securities and Markets Authority Wiki28 September 2026 · Verena RossWiki (Chair) Verena Ross' opening statement at the ECON hearing, 28 September 2026 Banking regulation and supervision CONTEXT Opening statement at the European Parliament's Economic and Monetary Affairs Committee (ECON), Verena Ross's last annual hearing as ESMA Chair. WHY IT MATTERS Reviews what has been achieved for EU capital markets and what is still missing to integrate them. PROBLEMS RAISED | 1. | Markets face high uncertainty and volatility. | | 2. | EU capital markets remain fragmented across national supervisors. | | 3. | Rules and reporting have become too complex. |
| SOLUTIONS PROPOSED | 1. | Keep removing unnecessary barriers between national markets. | | 2. | Apply risk-based, proportionate supervision. | | 3. | Maintain momentum on the capital markets reform package. |
|
FULL SUMMARY 1. A farewell hearing In her last appearance before the European Parliament's economic committee as ESMA Chair, Verena Ross reviewed the past year and her term. Amid geopolitical tension, trade disputes and fast technological change, she argued Europe needs deep and attractive capital markets to fund innovation and growth and let citizens share in it. 2. A year of integration and simplification She cited progress on consolidated market data feeds, the single access point for company information, preparation for next-day settlement, derivatives clearing rules and the Listing Act. Responding to industry complaints, ESMA proposed lighter transaction and fund reporting, a simpler path for retail investors and risk-based supervision, while insisting investor protection and market integrity stay intact. On crypto-assets, the focus has shifted from writing rules to supervising them consistently. 3. Looking ahead Innovation, she added, can only grow at scale where investors trust it, so good regulation and supervision enable rather than hinder it. Recalling that ESMA has grown over fifteen years through the debt crisis, Brexit and the pandemic, now supervising more firms directly and in close partnership with national authorities, she backed the market integration and supervision package now being negotiated and said ESMA is ready for any new direct-supervision tasks, urging lawmakers to keep up the pace and remove remaining barriers so that rules and supervision match an increasingly integrated market. |
| South African Reserve Bank Wiki28 September 2026 · Lesetja KganyagoWiki (Governor) Policy challenges of the new global disorder Monetary policy and interest rates · Inflation and price stability · Climate, energy and nature · Public finances and debt CONTEXT Address by Lesetja Kganyago, Governor of the South African Reserve Bank, at the Forum on Africa and Geopolitics, hosted by the Mapungubwe Institute for Strategic Reflection (MISTRA), Pretoria, 28 September 2026. WHY IT MATTERS Groups climate, imbalances, AI, debt and fiscal dominance as five pressures that test monetary policy in a more disordered world. PROBLEMS RAISED | 1. | Climate change and global imbalances are building up like a slow-moving disaster. | | 2. | Rapid technological change, chiefly AI, and heavy debt add to fragility. | | 3. | Fiscal dominance threatens the independence of monetary policy. |
| SOLUTIONS PROPOSED | 1. | Prepare early for gradual risks instead of waiting for a catastrophe. | | 2. | Keep public debt sustainable and fiscal policy credible. | | 3. | Protect central bank independence and its focus on price stability. |
|
FULL SUMMARY 1. A disaster as a metaphor Addressing a forum on Africa and geopolitics, South Africa's central bank governor opened with the glacier-driven flood that killed thousands in Nepal in August 2026. Dams in the valley had been designed for floods twenty times smaller than the one that came. He used the event as an image of a world where dangers build up quietly until a cascade of crises overwhelms ordinary precautions, and he listed five sources of danger. 2. Climate and geopolitics August 2026 tied the record for the hottest month, and current policies point to warming of about 2.6°C by 2100, well beyond the 1.5°C goal. For central banks this means more supply shocks, bursts of food inflation and insurance gaps that threaten financial stability. Geopolitics adds to the strain: disputes over Greenland and a tariff conflict pitting Canada against the United States, a fifth year of war in Ukraine with attacks on Black Sea grain routes and refineries, and an intensifying Middle East conflict that keeps oil near $100 and Saudi output at a thirty-year low. Supply disturbances, rather than demand, now drive the global cycle. 3. Imbalances, AI and debt Large trade imbalances have returned, with China's surplus under criticism, and history suggests they end abruptly and painfully, yet the trust needed for an IMF-led adjustment is missing. Artificial intelligence has advanced fast, with recent incidents of AI agents escaping controls and breaking into systems; he sees cyberattacks as a plausible trigger for the next financial crisis, alongside asset bubbles. Imagine, he said, a swarm of tireless automated agents breaking into the national payment system or a large financial firm. Public and private debt keep rising, long-term yields in rich countries are at multi-decade highs, the safety premium on US debt has faded, reserve managers are diversifying into gold and other currencies, and leveraged investors such as hedge funds increasingly set bond prices. 4. Fiscal dominance and central bank courage Many economists fear fiscal dominance, where a central bank tolerates inflation to ease the government's debt burden. He accepted the concern but rejected fatalism: central banking was never easy for South Africa, through the 2001 rand crisis, 2008, the 2013 taper tantrum, attacks on its independence and COVID-19. South African debt has roughly tripled since 2008 and interest absorbs about 5.3% of GDP, more than in the United States, Britain or France, yet he argued this calls for independence and courage, not surrender. Since inflation is poorly understood by the public and can be created quietly, central banks must make it the hardest option so that better fiscal choices win. 5. South Africa's position Inflation has been above the 3% target for about six months because of the war-driven energy shock, compared with more than five years of misses in the United States. The bank tightened policy and expects to return to target around the end of 2027. Public debt appears to have peaked in 2025/26, which has kept long-term yields near 9% and the rand stable while bond yields jumped elsewhere. Growth remains the weak point: about 0.6% a year over the past decade, with potential output now estimated around double that. The end of power cuts has been offset by the war and by electricity prices that doubled since 2020. 6. Conclusion The world is more dangerous and less governed than before, though growth and trade continue. South Africa, distant from conflict zones, young and rich in resources, has a better macroeconomic position than before, but it must recognise its new situation and act on its strengths, as little outside help is likely. |
| European Central Bank Wiki28 September 2026 · Christine LagardeWiki (President) Hearing of the Committee on Economic and Monetary Affairs of the European Parliament Inflation and price stability · Climate, energy and nature · Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Regular hearing before the European Parliament's economic committee in Brussels; the ECB keeps prices stable in the euro area and must explain its policy to elected representatives. WHY IT MATTERS Sets out how the ECB reads an energy shock: it reacts to the risk of embedded inflation, not to energy prices themselves. PROBLEMS RAISED | 1. | Outlook uncertainty is high, with upside inflation risks and downside growth risks. | | 2. | An energy shock is too large to look through. | | 3. | Short-term inflation expectations stay elevated. |
| SOLUTIONS PROPOSED | 1. | Respond only if energy price rises risk becoming embedded in inflation, with a measured reaction. | | 2. | Judge policy on the inflation outlook, underlying inflation and transmission. | | 3. | Support AI-driven productivity, which should ease inflation pressures over time. |
|
FULL SUMMARY 1. The economy and inflation Before the European Parliament's economic committee, ECB President Christine Lagarde said the euro area grew solidly in the second quarter despite the energy shock, helped by defence and infrastructure spending, recovering consumer confidence and AI-related activity; unemployment was 6.4% in July. Employment and labour-force growth are slowing while productivity edges up, and consumption, investment and exports should support activity as energy prices ease. In the staff baseline, annual growth picks up gradually from just under 1% this year to around 1.5% by 2028. Inflation rose to 3.2% in August as energy prices jumped 14.3%, driven by refining margins, while core inflation eased to 2.4% and wage growth slowed to 3.3%. Headline inflation is projected to average about 3% this year before slowing towards the 2% target by 2028, with core inflation peaking slightly above 2.5% next year; short-term expectations are elevated but longer-term ones remain close to 2%, and risks point to higher inflation and weaker growth. 2. Why the ECB raised rates She explained the September increase of 25 basis points. The ECB does not respond to energy prices as such, but to the risk that they become entrenched, judged on three criteria: the inflation outlook, underlying price dynamics and how policy transmits. Inflation is now expected to be higher in 2027–28, yet there is no sign of wages catching up, and higher long-term rates will cool the economy. She described the move as a measured middle path, since the shock is too big to ignore. 3. AI and the economy Firms plan to spend about a tenth of investment on AI in 2026, and about one euro in four of new corporate borrowing is now linked to AI. Higher productivity could lower costs and inflation over time, but adoption is shallow: 38% of firms report at least moderate use and only 7% heavy use, and investment trails the US. She also flagged financial risk from equity markets concentrated in a few heavily indebted AI firms. On jobs, over half of workers already use AI and firms keep hiring, especially those using it to innovate rather than cut costs; whether it mainly complements or replaces workers remains open. She urged Europe to foster AI innovation through a deeper single market, capital markets and cheaper energy, strengthen weak links in the AI supply chain without seeking autarky, and spread deep adoption through retraining. European schemes such as InvestAI, the Scaleup Europe Fund and EUR 30 billion for AI gigafactories are, in her view, a good start. For monetary policy, the ECB will track how AI changes productivity, investment, jobs, financial conditions and prices, arguing that uncertainty is no excuse for inaction. |
| Asian Infrastructure Investment Bank Wiki28 September 2026 · Zou JiayiWiki (President) AIIB President’s Opening Remarks at the 11th AIIB Annual Meeting, Doha, Qatar Development and emerging economies CONTEXT Opening of the 11th Annual Meeting in Doha of the Asian Infrastructure Investment Bank, whose mission is to finance infrastructure in Asia, while the region's needs far exceed available funding. WHY IT MATTERS The AIIB's yearly gathering of its member governments: the President sets out where the bank wants to put its effort next, notably on preparing projects before they are financed. PROBLEMS RAISED | 1. | Infrastructure needs of member countries remain large. | | 2. | Projects are often poorly prepared before financing. | | 3. | Borrowers face currency risk on foreign-currency loans. |
| SOLUTIONS PROPOSED | 1. | Engage earlier in the project cycle and invest in upstream work. | | 2. | Strengthen project preparation support. | | 3. | Broaden the financing toolkit, including local-currency options. |
|
FULL SUMMARY 1. A new president's first annual meeting Opening the Asian Infrastructure Investment Bank's 11th annual meeting in Doha, President Zou Jiayi noted the bank now counts 111 members, has approved over USD 79 billion for more than 400 projects in 43 economies and keeps top credit ratings. After visiting more than 30 members, including a ride on a rapid-transit line near Delhi that the bank helps fund, she said members consistently ask for more infrastructure and more financing. 2. Plans for the next decade The bank aims to roughly double yearly lending to about USD 20 billion by 2030, focusing on climate resilience, renewables, digital networks, regional links, nature and social infrastructure, while drawing in more private capital. It will move closer to clients, open more offices, engage earlier in project preparation and offer more local-currency financing, with integrity and high standards as guiding principles. 3. Cooperation She presented development as a shared agenda among equal partners, noted Asia needs some USD 3 trillion of infrastructure investment a year, and said the bank will keep its Asian focus while staying open to members from other regions. |
| European Securities and Markets Authority Wiki24 September 2026 · Verena RossWiki (Chair) Verena Ross' speech at the International Conference on Finance, Warsaw, 23 September 2026 Banking regulation and supervision · Development and emerging economies CONTEXT Keynote at the International Conference on Finance in Warsaw, held for the 20th anniversary of the Polish Financial Supervision Authority (KNF). WHY IT MATTERS The ESMA Chair presents the market integration package as possibly the biggest EU market reform since the post-crisis years. PROBLEMS RAISED | 1. | Fewer companies list on public markets and more delist. | | 2. | The EU lags other major markets in depth and scale. | | 3. | Retail investors lack confidence to invest. |
| SOLUTIONS PROPOSED | 1. | Adopt the market integration and supervision package. | | 2. | Give legal certainty to DLT-based market infrastructures. | | 3. | Make the investor journey simpler for retail savers. |
|
FULL SUMMARY 1. Poland as an example At an international finance conference in Warsaw marking 20 years of Poland's financial supervisor, ESMA Chair Verena Ross traced how Polish capital markets were built from scratch three decades ago through new laws, infrastructure and supervision. The Warsaw exchange now lists over 400 companies, is the largest in Central and Eastern Europe, and foreign investors make up nearly three-quarters of trading, which she credits to bold privatisation and market policies, EU membership and its common investor-protection rules, and strong national oversight that turned those rules into local confidence. 2. Europe's weaknesses EU reforms on listing rules, company data access, consolidated trading data and settlement in one day from October 2027 help, but she points to fewer listings, more delistings, limited investment capacity and fragmentation that some estimate has cost trillions of euros of output. Retail and institutional investment remain too small to meet Europe's long-term needs, from defence spending to the climate and digital shifts, which also means lost opportunities for savers: Polish households save about 10% of income and invest about 5%, well below EU averages of roughly 15% and 9%. Earlier reforms, however successful, are therefore not enough, and she calls for renewed ambition. 3. The integration package She welcomes the savings and investments union and its market integration and supervision package, which could be the most important market reform since the post-crisis era. EU-level supervision would suit truly pan-European players such as large trading venues, clearing houses, securities depositories and crypto firms, provided the criteria are realistic and ESMA works closely with national authorities while having the means to act independently. Common rules must produce common outcomes, which requires convergence tools and consistent supervision, plus cooperation arrangements tailored to each sector that avoid duplication. The package would also harmonise trading rules, allow trading groups to operate under one licence, link securities depositories through a hub model with standardised connections, and make the pilot regime for distributed-ledger infrastructure more usable so that tokenised markets can grow beyond trials. 4. Simpler rules She stresses lighter reporting for firms and funds, an easier path for retail investors and risk-based supervision, noting Poland's supervisor has also removed national add-ons. Safeguards must stay, but the system must become leaner and more agile, combining national expertise with European ambition. |
| 24 September 2026 · Fabio PanettaWiki (Governor) The challenge of innovation Financial stability · Trade, fragmentation and geopolitics · Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Address by Fabio Panetta, Governor of the Bank of Italy, at the 10th Annual Research Conference of the National Bank of Ukraine and the National Bank of Poland “Central banks response to future challenges: resilience, credibility, and innovation”, Kyiv…. WHY IT MATTERS Spoken in Kyiv, this speech links war, economic coercion and technology to one question: how central banks stay credible and independent under heavy pressure. PROBLEMS RAISED | 1. | Wars and geopolitical fragmentation make the economic environment more volatile. | | 2. | Economic and financial dependencies are being used as weapons. | | 3. | Fast technological change challenges how central banks keep their credibility. |
| SOLUTIONS PROPOSED | 1. | Protect central bank independence and the capacity to act under pressure. | | 2. | Build resilience, learning from Ukraine's central bank experience. | | 3. | Adapt to innovation rather than resist it, to stay credible. |
|
FULL SUMMARY 1. Credibility tested in two ways In Kyiv, at a research conference jointly organised by the Ukrainian and Polish central banks, the Governor of the Bank of Italy expressed solidarity with Ukraine and argued that central bank credibility sometimes requires standing firm and sometimes adapting. Geopolitical conflict tests the first quality; artificial intelligence and digitalisation test the second. 2. Lessons from the hryvnia Ukraine's currency turned thirty in 2026. After the 2014-15 crisis, when it lost over half its value and banks were restructured, the National Bank of Ukraine adopted inflation targeting, a more flexible exchange rate and risk-based supervision. These reforms allowed it to keep monetary and financial stability after the 2022 invasion: inflation passed 26%, the policy rate went to 25%, banks kept working and inflation later fell. A new four-year IMF programme approved in February 2026 recognised this record, while alignment with EU banking rules progressed. The lesson is that credibility is accumulated in calm times and proven in extreme ones. 3. AI and the economy Generative AI is spreading faster than personal computers or the internet did. Central banks must understand it, both as an analytical tool and as a force changing the economy. In the short run, AI investment lifts demand and prices for computing power, energy and specialised staff. In the long run, productivity gains could be large; Bank of Italy research suggests more than one extra point of annual labour productivity growth for Italy. Such a supply gain would normally mean more growth and lower inflation, but its timing and size are uncertain and it also affects incomes and spending. 4. Demand, inequality and gaps between countries Should AI chiefly generate new kinds of work and lift expected wages, households may spend more and inflation could last longer; if it mainly replaces workers, precautionary saving could bring disinflation sooner. The outcome will be uneven across workers and firms, possibly favouring large companies. Central banks will therefore need to know who gains, not only how much. Between countries, the United States leads in AI investment, which widens its trade deficit and draws foreign money into its stock market, while Europe lags but could still catch up through adoption. Faster adopters may win lasting productivity and market share, with possible swings in exchange rates whose direction is hard to predict. 5. Consequences for policy The effect of AI on the neutral interest rate is ambiguous: faster productivity pushes it up, while inequality, extra saving or a larger capital share pull it down. Stock valuations built on optimistic AI profits leave room for abrupt corrections. He therefore recommended pragmatism, giving observed demand, activity and inflation more weight than estimates of unobservable variables, and investing in skills and models. 6. Supervision and payments AI can improve credit scoring, fraud detection and risk control, but common models or a few technology suppliers could spread errors across the system, so supervisors need deeper technical knowledge. New payment providers raise efficiency but also complexity and cyber risk. The two-tier system, in which public money issued by the central bank anchors the private services built on it, should be adapted rather than abandoned. Stable prices, a sound financial system and public confidence in money stay the foundations. |
| U.S. Commodity Futures Trading Commission Wiki22 September 2026 · Michael S. Selig (Chairman) Keynote Remarks at 2026 U.S. Treasury Market Conference CONTEXT Speech by Michael S. Selig, Chairman of the U.S. Commodity Futures Trading Commission. |
| 22 September 2026 · Joachim NagelWiki (President) Has Europe fully digested the new geoeconomic realities - and does it have the energy to cope with them Climate, energy and nature · Trade, fragmentation and geopolitics · Growth, investment and productivity CONTEXT Evening speech by the Bundesbank President to the Society of Professional Economists in the United Kingdom. WHY IT MATTERS The Bundesbank President, speaking in London, argues that Europe's old growth drivers are fading and calls for closer EU-UK cooperation in a fragmenting world. PROBLEMS RAISED | 1. | Geoeconomic fragmentation is reshaping the world economy. | | 2. | The forces that supported European growth are weakening. | | 3. | The EU and the UK face similar pressures. |
| SOLUTIONS PROPOSED | 1. | Acknowledge the new geoeconomic realities. | | 2. | Deepen EU-UK cooperation and regulatory alignment where useful. | | 3. | Mobilise Europe's energy to strengthen its economy. |
|
FULL SUMMARY 1. Britain and the EU, closer again At the annual dinner of a British society of economists in London, the Bundesbank President noted that, ten years after the referendum, the United Kingdom has drifted less from EU rules than many expected and now seeks closer ties, from youth mobility to defence. He explained this rapprochement by a shared exposure to geoeconomic fragmentation, which the IMF describes as a deliberate unwinding of integration for strategic reasons. 2. The new geoeconomic landscape The rivalry between Washington and Beijing now defines the world economy, and each side uses chokepoints. China dominates rare earths and produces around 30% of world manufacturing, threatening Europe's mid-technology industry. The United States controls most global financial services, leads in technology and anchors NATO, and it now uses tariffs as leverage. Bundesbank work shows tariffs hurt trade and the US economy itself, although the AI investment boom kept world trade strong last year. Trade restrictions reached record numbers in 2023-25 and trade policy uncertainty in this decade is about five times the level of the 2000s. German exporters were squeezed by both US tariffs and Chinese competition, France worries about Chinese export pressure and British analysts see these forces aggravating domestic weaknesses. 3. Europe's assets He answered his own question with confidence: Europe can cope. Britain brings world-class finance and professional services, advanced manufacturing and an educated workforce; the EU brings the largest trading bloc and network of trade deals, strong industry and a market of 27 countries and 450 million consumers. The friendship treaty signed between Britain and Germany last year expresses the shared values on which both can build. 4. Competitiveness and digital money The EU still has to exploit its single market fully. The savings and investments union aims to channel European savings into European investment, with further plans to close the funding gap for growing start-ups and to let a new company be created online in two days for at most €100. In payments, a digital euro would bring central bank money into the digital era and reduce reliance on non-European card schemes; legislation is expected by the end of 2026 and a launch in 2029. A wholesale settlement service linking tokenised markets to the Eurosystem's payment platforms began operating the day before the speech. 5. Artificial intelligence and security AI promises large efficiency gains, already visible in early uses including at central banks, but frontier models also raise cyber risks for financial stability, as the Financial Stability Board has warned. Britain and the EU cooperate on these issues through regular dialogues. He concluded that, by combining their strengths and common values, both will absorb the shock and become more resilient. |
| 21 September 2026 · Tiff MacklemWiki (Governor) Navigating uncertainty and adapting to change Monetary policy and interest rates · Inflation and price stability · Trade, fragmentation and geopolitics · Growth, investment and productivity CONTEXT Speech by the Governor of the Bank of Canada to a business audience invited by the Halifax Partnership in Halifax, Nova Scotia. WHY IT MATTERS The Bank of Canada Governor explains how US tariffs and the Middle East conflict pull growth and inflation in opposite directions, and what that means for the policy rate. PROBLEMS RAISED | 1. | US tariffs and trade tensions weigh on Canadian exporters. | | 2. | The Middle East conflict raises the risk of broader, persistent inflation. | | 3. | Growth prospects are uncertain while inflation risks point upward. |
| SOLUTIONS PROPOSED | 1. | Keep inflation anchored on the 2% target. | | 2. | Reassess whether the policy rate balances growth and inflation risks. | | 3. | Raise rates only if inflation pressures prove persistent. |
|
FULL SUMMARY 1. From shock to adaptation In Halifax, Bank of Canada Governor Tiff Macklem returned to the structural forces he described in February: trade conflict with the United States, artificial intelligence and ageing. He sees firms moving through three phases: first pausing to reassess, which stalled growth in 2025 and early 2026; then adapting through quick, reversible adjustments; and finally transforming through investment, new products and new markets, which is what lifts productivity. 2. Signs that firms are adjusting Non-energy exports jumped 14.5% in the second quarter, their highest since early 2025, as firms cut tariff exposure, rearranged supply chains and sold more to existing customers outside the US. Employers slowed hiring rather than firing in 2025, and private hiring has picked up this year. On AI, nearly one in five businesses used it in production in the past year, about three times the share two years earlier, mostly for routine tasks; firms change the skills they seek more than their headcount, though finding work has become harder in the most exposed jobs. Labour-force growth will be close to zero because of ageing. Business investment rose at an 8.8% annualised pace, and over two-thirds of exporters plan to enter new markets, while governments work on infrastructure, internal trade barriers and new trade deals. 3. Two new threats First, trade talks broke down and new US tariffs hit products worth about 5% of goods exports to the US; the direct effect is limited, but renewed uncertainty may make firms hold back again, possibly halving fourth-quarter growth to under 1%. Second, the Middle East conflict has lasted longer than expected. Damaged refineries have made fuel far dearer than crude prices alone would imply, as if oil were about USD 40 higher, keeping inflation near 3%; with oil around USD 100 it could rise further. Canadian counter-tariffs should add little to prices. Bond yields are rising worldwide on heavier borrowing and expectations of tighter policy. The result is weaker growth on one side and higher inflation risk on the other, while many households still feel squeezed by past price rises. 4. The Bank's approach The Bank has so far looked through the direct effect of oil, as costs have not spread widely, but the risk that inflation broadens has grown. The key questions are whether firms pass on costs and whether expectations drift up, against the dampening effect of slack in the economy. Policy works with a lag, so the Bank must judge which pressures are temporary and which will last, separating cyclical from structural forces. He calls for lower tariffs given how integrated the two economies are, noting that Canada is the top export market for most US states and that a full return to the old relationship is unlikely, describes a new forecasting model, Prima, to be used from the October report, and explains the decision to hold rates in September. The Bank will raise rates only if inflation pressures prove lasting, and stands ready to adjust. |
| European Securities and Markets Authority Wiki18 September 2026 · Verena RossWiki (Chair) Verena Ross' speech at Eurofi Dublin, 17 September 2026 Banking regulation and supervision · Trade, fragmentation and geopolitics · Technology, AI and cyber risk CONTEXT Speech by the ESMA Chair at the Eurofi conference in Dublin, a meeting of EU policymakers and financial industry leaders. WHY IT MATTERS At Eurofi, the ESMA Chair warns that too many carve-outs could empty the reform of EU-level supervision of its purpose. PROBLEMS RAISED | 1. | Supervision of cross-border firms is fragmented and duplicative. | | 2. | Divergent national expectations create uneven outcomes. | | 3. | Technology, cyber risk and geopolitics make markets more complex. |
| SOLUTIONS PROPOSED | 1. | Strengthen EU-level supervision of significant cross-border entities. | | 2. | Avoid carve-outs that would weaken the reform. | | 3. | Cut complexity that adds little value while keeping strong oversight. |
|
FULL SUMMARY 1. Markets that are European need supervision that is too Speaking at the Eurofi conference in Dublin, ESMA Chair Verena Ross argued that firms, risks and data now cross borders so quickly that oversight confined to one country no longer fits. The EU wants deeper, more liquid markets, wider investment choice for savers and easier company funding, and she links that goal to the Commission's market integration and supervision package. Moving certain large cross-border entities under EU-level supervision is, in her view, a practical step rather than centralisation for its own sake: if firms meet different expectations in each state, they simply organise themselves around the fragmentation. 2. Simpler does not mean weaker Ross ties the reform to burden reduction. Part of the complexity firms face comes from the rules, but part comes from uneven national application, repeated requests and slow coordination. A single integrated supervisor for truly cross-border activities could cut duplication, speed up time to market, make better use of data and let scarce expertise focus on the biggest risks. She insists this is not about doing less: cyber threats, new technology and geopolitical uncertainty make the supervised world harder, so the aim is to remove low-value complexity, not vigilance. 3. A message to lawmakers With the Council and Parliament both aiming to settle their positions by the end of the year, she urges them not to dilute the proposal. Clear responsibilities, simple governance and matching resources are needed. A text riddled with exceptions, partial transfers or boundaries drawn to shield national champions, or EU supervision merely stacked on top of existing arrangements, would keep fragmentation alive while only looking European. She recalls that ESMA was born after a crisis, has matured since, and will implement whatever is agreed. |
| 18 September 2026 · Kyriakos PierrakakisWiki (President) Remarks by Kyriakos Pierrakakis following the Eurogroup meeting of 18 September 2026 Climate, energy and nature · Public finances and debt · Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Press conference by the Eurogroup President after the monthly meeting of euro area finance ministers on 18 September 2026. WHY IT MATTERS The euro area's common line on paying for defence, digital and energy needs while budgets stay tight. PROBLEMS RAISED | 1. | Euro area growth and productivity need strengthening. | | 2. | Large investment needs in defence, digital and energy. | | 3. | Budgets are constrained. |
| SOLUTIONS PROPOSED | 1. | Increase investment in defence, digitalisation and energy. | | 2. | Choose investments that also boost growth. | | 3. | Coordinate fiscal policies within the Eurogroup. |
|
FULL SUMMARY 1. Resilient growth, rising pressure After the Eurogroup meeting in Dublin, President Kyriakos Pierrakakis said the euro area did better than expected in the second quarter and should keep expanding through the end of 2026. He then listed multiplying challenges: Middle East developments are pushing oil and gas prices up again, and tighter global financial conditions have lifted government bond yields everywhere, adding strain to national budgets. Spreads inside the euro area remain modest compared with past crises, which he attributes to past tough choices, sturdier institutions and more prudent budgets. 2. Energy independence and fiscal discipline His answer is to reduce dependence on events abroad by speeding up energy independence, and to stay on the agreed fiscal path because credibility has become an economic asset. If higher energy prices call for new support, it should be narrow in scope, short in duration and compatible with the budget rules. Investment in defence, digitalisation and energy should continue, and public spending should be made more effective, a topic the ministers will take up again next month. 3. Productivity and Europe's savings Ministers also heard OECD Secretary-General Mathias Cormann on productivity, two years after the Draghi report. Pierrakakis said progress is real but the world is moving faster. The priorities he named: skills and education suited to an AI-driven economy, steering capital, labour and technology towards their most productive uses, faster spread of innovation, higher productivity in services, and channelling European savings into growing firms through a deeper Single Market. Europe, he concluded, knows many of the solutions and must now deliver them. |
| 18 September 2026 · Joachim NagelWiki (President) Opening remarks - panel session on economics of innovation Development and emerging economies · Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Opening remarks by Joachim Nagel, President of the Deutsche Bundesbank, at the panel session on economics of innovation, at the Central Bank of Ireland conference “Trust and innovation – the future of finance", Dublin, 18 September 2026. WHY IT MATTERS A clear diagnosis from the Bundesbank of why Europe struggles to turn innovation into growth, with a concrete list of fixes from capital markets to data centres. PROBLEMS RAISED | 1. | Europe struggles to create and scale productivity-boosting innovation. | | 2. | Its venture capital market is far smaller than in the United States. | | 3. | Infrastructure gaps, including data centres, hold back growth. |
| SOLUTIONS PROPOSED | 1. | Complete the single market and a savings and investments union. | | 2. | Improve infrastructure, education and basic research. | | 3. | Let the public sector set reliable rules and act only where markets fail. |
|
|
| Reserve Bank of Australia Wiki18 September 2026 · Michele BullockWiki (Governor) Opening statement - House of Representatives Standing Committee on Economics Monetary policy and interest rates · Inflation and price stability · Financial stability · Payments, digital money and crypto-assets CONTEXT Opening statement by Michele Bullock, Governor of the Reserve Bank of Australia, to the House of Representatives Standing Committee on Economics, Canberra, 18 September 2026. WHY IT MATTERS The Reserve Bank of Australia's Governor accounts to Parliament for rising inflation, naming the conflict, the AI boom and extreme weather as price drivers. PROBLEMS RAISED | 1. | Inflation is rising because of capacity pressures in the economy. | | 2. | The Middle East conflict, the AI boom and extreme weather push up prices. | | 3. | Weak productivity growth limits how fast the economy can grow. |
| SOLUTIONS PROPOSED | 1. | Keep monetary policy focused on bringing inflation back down. | | 2. | Strengthen the resilience of critical payment infrastructure. | | 3. | Keep reforming governance, risk management and culture at the RBA. |
|
FULL SUMMARY 1. Inflation back above target In her opening statement to an Australian parliamentary committee, RBA Governor Michele Bullock explained that the Monetary Policy Board has raised the cash rate by 50 basis points since February, 75 this year, because inflation, after returning to the 2-3% band in 2024-25, rose again in the second half of 2025 and now runs around or slightly above 3.5%. She blames domestic capacity pressure plus the Middle East conflict, which lifts fuel prices directly and, as firms pass on costs, indirectly. Forecasts put inflation back near the target midpoint only in late 2027. Unemployment of 4.5% shows a labour market a little tighter than full employment. 2. Risks and the housing market Upside inflation risks are materialising: global cost pressure from the Middle East, the AI boom and extreme weather; firms passing on higher input costs; and a risk that capacity strain worsens pass-through. Growth is slowing and the full effect of past rises is still to come, but business investment, mainly data centres and renewables, is strong, and weak productivity means the economy cannot grow quickly without adding inflation. Housing prices have eased but remain about 50% above early 2020, few borrowers are in negative equity and savings buffers are large, so financial stability risks look contained. She stressed that policy does not target house prices; they matter through wealth, turnover and construction. Whether tightening so far is enough will be examined at the next meeting, and she acknowledged the pain for mortgage holders while insisting that high inflation hurts everyone, especially lower incomes. 3. Payments, cash and tokenisation On payments, card surcharging will be banned from 1 October alongside lower interchange caps and more transparent costs; a wider review of payments regulation will publish priorities by the end of 2026, covering mobile wallets, three-party schemes, direct bank-to-bank transfers and AI-agent purchasing. Project Acacia found that tokenisation plus new settlement infrastructure could improve efficiency and resilience; a consultation on the bank's own settlement system follows, a tokenisation sandbox is being explored, and there is still no clear case for a retail digital currency. For cash, about half of Australians use it weekly; a new law gives crisis powers, the cash carrier Linfox Armaguard has been designated, and the ACCC will oversee pricing and access. 4. A more open RBA She finished by reporting that the bank has completed the remaining recommendations of its independent review, including a framework for extra policy tools and an external expert advisory group, and is committed to continuous improvement in governance, risk and resilience. |
| 18 September 2026 · Emmanuel MoulinWiki (Governor) The importance of being earnest - building a simpler and more competitive European banking market Financial stability · Banking regulation and supervision · Climate, energy and nature · Trade, fragmentation and geopolitics CONTEXT Speech by the Governor of the Banque de France in Dublin, at the invitation of the Eurofi conference organisers. WHY IT MATTERS The new Banque de France Governor makes the case for truly European banking groups and simpler rules, a central debate in EU financial policy. PROBLEMS RAISED | 1. | European banks are losing ground to foreign groups in corporate and investment banking. | | 2. | Fragmentation prevents truly European banking groups from emerging. | | 3. | Europe must finance climate, digital and defence priorities in a fragmented world. |
| SOLUTIONS PROPOSED | 1. | Remove the fragmentation that blocks cross-border European banking groups. | | 2. | Simplify prudential rules while keeping banks resilient. | | 3. | Adapt the framework to the financing needs of the European economy. |
|
FULL SUMMARY 1. Strong banks, lost ground At the Eurofi forum in Dublin, the Governor of the Banque de France observed that fifteen years of reform have left EU banks with record capital and liquidity, yet foreign groups now handle about 60% of corporate and investment banking for European clients. Solidity alone will not finance the climate transition, digital needs, defence and Europe's financial autonomy. 2. A single banking market Cross-border loans are under 15% of euro area lending and cross-border mergers are rare, because groups must still hold capital and liquidity country by country. He called for waivers allowing groups to manage them centrally, with guarantees that parents support subsidiaries in stress, without waiting for a common deposit insurance scheme. 3. Simpler rules, not weaker ones Simplification must not mean deregulation: Basel III was right and must stay risk-based and uniform. He proposed aligning loss-absorbing debt requirements, removing overlaps between supervisory add-ons and minimum rules, and questioning EU-specific buffers. Delaying the trading book capital rules for 2027-30 protects competition with other regions, but a lasting answer is needed. 4. Financing Europe Better internal models justify reviewing the output floor where it duplicates other safeguards, keeping lower capital charges for low-risk mortgages and possibly some unrated firms, and easing EU-only extras on trade and specialised finance. Revised securitisation rules should also widen market funding. |
| New Development Bank (BRICS) Wiki15 September 2026 · Dilma RousseffWiki (President) Address by NDB President Dilma Rousseff at the 18th BRICS Summit, Open Plenary Session Financial stability · Public finances and debt · Trade, fragmentation and geopolitics · Development and emerging economies CONTEXT Address to heads of state and government at the open plenary session of the 18th BRICS Summit, held under India's BRICS presidency. WHY IT MATTERS The BRICS bank's head addresses the leaders' summit itself, presenting national-currency finance as the members' answer to sanctions, tariffs and exchange-rate swings. PROBLEMS RAISED | 1. | Wars, sanctions and tariffs disrupt trade and investment. | | 2. | Debt vulnerabilities and unmet development goals persist. | | 3. | Exchange-rate volatility hurts investors. |
| SOLUTIONS PROPOSED | 1. | Use national currencies to support investment. | | 2. | Strengthen domestic capital markets. | | 3. | Share technologies and solutions among members. |
|
|
| 15 September 2026 · Kyriakos PierrakakisWiki (President) Press remarks by the Eurogroup President after his meeting with Lars Klingbeil, Vice Chancellor of Germany and Federal Minister of Finance Public finances and debt CONTEXT Press remarks by the Eurogroup President after meeting Lars Klingbeil, Germany's Vice Chancellor and Finance Minister. WHY IT MATTERS The Eurogroup's message to the largest euro economy: reforms and sound budgets together. PROBLEMS RAISED | 1. | Europe's economic performance is too weak. | | 2. | Public finances must remain sustainable. | | 3. | Reforms are difficult to deliver. |
| SOLUTIONS PROPOSED | 1. | Strengthen economic performance through reforms. | | 2. | Keep fiscal sustainability commitments. | | 3. | Learn from countries that delivered rapid reforms. |
|
FULL SUMMARY 1. A hard backdrop Meeting Germany's finance minister Lars Klingbeil ahead of the Dublin Eurogroup, President Kyriakos Pierrakakis described an exceptionally difficult setting: the war in Ukraine, instability in the Middle East, and high energy costs and price pressure weighing on firms and households. Euro-area growth has nevertheless held up better than feared. 2. Beyond budget discipline He says sound public finances matter but will not alone bring growth or economic sovereignty. Structural obstacles must be tackled: a deeper Single Market, a faster savings and investments union, and an energy market less split by national borders. Fiscal room will shrink as defence, ageing and climate costs rise, so the Eurogroup will review revenue, spending and governance in the coming months, push the market integration and supervision package, and open a strategic debate on AI and technological sovereignty, alongside energy security, critical minerals and climate adaptation. 3. A lesson from Greece Drawing on his experience as Greece's finance minister, he argued that painful reforms pay off politically, economically and socially, pointing to his country's fast-falling debt, positive growth and primary surpluses. The goal, he said, is a European economy less exposed to outside shocks. |
| 15 September 2026 · Ayman M Al-Sayari (Governor) Keynote speech - Money20/20 Middle East Banking regulation and supervision · Payments, digital money and crypto-assets · Development and emerging economies · Growth, investment and productivity CONTEXT Keynote speech by His Excellency Ayman Al-Sayari, Governor of the Saudi Central Bank, at the Money20/20 Middle East, Riyadh, 15 September 2026. WHY IT MATTERS Shows Saudi Arabia's regulatory approach to fintech and its cautious engagement on stablecoins and virtual assets. PROBLEMS RAISED | 1. | Fast-growing fintech must not outrun stability and trust. | | 2. | Stablecoins and virtual assets carry risks that need safeguards. | | 3. | Global uncertainty weighs on investor confidence. |
| SOLUTIONS PROPOSED | 1. | Provide licensing pathways, supervisory tools and shared infrastructure that lower entry barriers. | | 2. | Engage with global regulators to design safeguards for digital assets. | | 3. | Build agile frameworks in partnership with industry that balance innovation and stability. |
|
|
| U.S. Securities and Exchange Commission Wiki14 September 2026 · Paul S. Atkins (Chair) Remarks at the Solana Policy Institute Summit: Washington x Wall Street Payments, digital money and crypto-assets · Development and emerging economies CONTEXT Speech by Paul S. Atkins, Chair of the U.S. Securities and Exchange Commission. WHY IT MATTERS The SEC Chair lays out the next steps of his crypto agenda, from token offerings to custody rules for funds. PROBLEMS RAISED | 1. | Crypto entrepreneurs lack regulatory certainty in the US. | | 2. | Market infrastructure such as transfer agents is outdated. | | 3. | Rules on crypto custody for funds and advisers are unclear. |
| SOLUTIONS PROPOSED | 1. | Finalise clear rules for token offerings. | | 2. | Modernise transfer agent rules for blockchain records. | | 3. | Propose a crypto custody framework for advisers and funds. |
|
FULL SUMMARY 1. A race for crypto leadership Addressing a Solana Policy Institute summit in Washington, SEC Chairman Paul Atkins framed the moment as a choice between building the future of finance in America or ceding it abroad. He presented the agency's Project Crypto as a rule-by-rule effort to make the country the world's crypto capital, and urged Congress to pass the CLARITY Act, adding that the administration will act with or without it. 2. Three proposals First, the proposed Regulation Crypto Assets would let founders raise money using digital assets under clear securities rules; the main feedback asks when an investment contract ends once promised work is done. Second, transfer-agent rules left untouched for about forty years, written for paper certificates, are proposed for modernisation toward tokenised shares. Third, staff are drafting a proposal that would let advisers and regulated funds hold crypto, including self-custody where no qualified custodian exists and through state trust companies. 3. One architecture and a warning Atkins presents these as three pillars of one framework covering the whole life of a digital asset: its creation, its trading, its transfer and its safekeeping. Citing a Jefferson line about institutions keeping pace with the times, he warned that failing to adapt would send blockchain finance's best advances overseas, and promised clarity while staying within the SEC's statutory mission. |
| Reserve Bank of India Wiki14 September 2026 · Sanjay MalhotraWiki (Governor) Winning in the AI era - the new playbook for Indian banks Financial stability · Technology, AI and cyber risk CONTEXT Inaugural address by Sanjay Malhotra, Governor of the Reserve Bank of India, at the Annual Financial Institution Benchmarking and Calibration (FIBAC) 2026 Conference, organised jointly by the Federation of Indian Chambers of Commerce and Industry …. WHY IT MATTERS One of the most concrete central bank texts on AI risk in banking, with specific demands on vendor contracts, audits and stress tests. PROBLEMS RAISED | 1. | Similar AI trading models could amplify market volatility under stress. | | 2. | Banks depend on outside AI vendors with little accountability. | | 3. | Digital fraud and underserved small-business credit remain big gaps. |
| SOLUTIONS PROPOSED | 1. | Invest in technology, talent and AI governance. | | 2. | Write audit, explanation and exit rights into AI outsourcing contracts. | | 3. | Stress-test AI systems before and after deployment, following RBI guidelines. |
|
FULL SUMMARY 1. AI as a new way of banking Speaking at the FIBAC conference, Reserve Bank of India Governor Sanjay Malhotra said AI will mark the 2020s for Indian banks, much as liberalisation marked the 1990s and digitalisation the 2010s. It is not a product to buy but a shift in how banks assess danger, look after clients, set the price of capital and structure their organisations; the choice is whether to steer it deliberately or be shaped by it. He first recapped last year's three regulatory priorities: Basel III is on track for April 2027, regulatory burden on boards and forms has been cut, and public digital rails such as Account Aggregator and the Unified Lending Interface are lowering the cost of credit, especially for small firms. 2. Five reasons to engage The RBI sees AI as a capability to harness, not merely a risk. He gave five arguments. Credit: models using cash flows, tax filings and utility payments can reach borrowers with no credit history at far lower cost, and spot stress earlier. Service: tools that assist, not replace, relationship managers and complaint handling. Inclusion: voice interfaces in Indian languages and early-warning models that allow counselling before default. Efficiency: automating document processing, reconciliation, audit sampling and regulatory reporting to cut costs. Fraud: machine-learning systems that learn from transaction patterns can catch anomalies in real time, where fixed rules always lag. Each bank should write its own playbook, backed by board-driven strategy and sustained investment in infrastructure, skills, partnerships and governance. 3. Seven risks He then listed seven risks. Opaque black-box models undermine accountability when a loan is refused. Bias can reproduce historic discrimination by region, occupation or community, so fairness must be designed in from day one. Concentration and herding arise if a few foundation models or vendors underpin decisions, turning one flaw into a systemic one and synchronising trading in stress. Vendor dependence requires contracts with audit, explanation and exit rights. On data privacy, the data-protection law is the minimum, not the maximum. Cyber and adversarial attacks, such as data poisoning, can target AI defences. Finally, human judgment must not erode: blaming the model is never acceptable, so oversight and the ability to intervene and override must remain. 4. What the RBI expects and offers Following its FREE-AI committee and draft model-risk guidelines, the RBI takes a principles-based, proportionate approach, treating innovation and safety as complementary. Banks should keep a full inventory of AI systems including vendor-embedded ones, adopt board-approved governance with clear accountability, be able to explain decisions affecting customers, stress-test and red-team models before and after launch, and keep human oversight wherever harm could result. The RBI promises consultative, evidence-based supervision, its regulatory sandbox, and shared tools such as MuleHunter and a planned Digital Payments Intelligence Platform. The winners, he concludes, will adopt AI with understanding, accountability and customer trust. |
| European Central Bank Wiki14 September 2026 · Christine LagardeWiki (President) A new age of capital: growth, sovereignty and AI Development and emerging economies · Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Lecture in Vienna to an audience of policymakers and economists; the ECB keeps prices stable in the euro area and faces weak investment and growing strategic dependence. WHY IT MATTERS Treats AI as a capital-intensive buildout and warns that Europe needs its own models, infrastructure and financing to avoid dependence. PROBLEMS RAISED | 1. | Europe depends on foreign AI models and infrastructure and risks being cut off. | | 2. | Closing the data-centre gap could cost hundreds of billions of euros. | | 3. | Savers are exposed to US tech giants and a sharp correction. |
| SOLUTIONS PROPOSED | 1. | Develop good-enough models running on European infrastructure. | | 2. | Draw the whole capital market into the buildout, from bonds to securitisation. | | 3. | Let companies adopt AI on its merits through a world of many, including open, models. |
|
FULL SUMMARY 1. A lesson from the 1870s Speaking in Vienna, Christine Lagarde recalled the Gründerzeit before 1873, when European savers financed the technologies of the day, the Suez Canal and, in far larger sums, American railways, in what Hobsbawm called the age of capital. After the 1873 crash, the assets and the growth stayed on American soil, and America overtook Europe while Europe stagnated for two decades. Today European savers are again funding the defining technology, AI, mostly in the US: about 440 billion euros of American tech equity sits in euro area household portfolios. She asks whether Europe will capture a fair part of the gains this time. 2. Why Europe must adopt fast Europe is doing better than its reputation: euro area firms will put about 10% of investment into AI in 2026, AI-related borrowing explains about a quarter of business credit growth in the first quarter, and worker use has doubled in two years to over half. Yet US digital investment grew twice as fast, and US workers use AI two to three times more. Speed matters because ageing strains the social model, over 100 billion euros a year of public investment needs are unfunded, and the working-age population is set to fall by over a million people annually, so only faster productivity growth can pay for it; ECB estimates say quick adoption could raise productivity by up to 4% within a decade. Europe also bears the cost of the boom regardless of whether it captures any gain: US hyperscalers issued over 100 billion dollars of bonds last year, lifting long-term yields that euro area rates follow. 3. Why importing is not enough Unlike in 1873, the companies are now built elsewhere: the US produced 59 notable AI models last year and China 35, France and the UK one each, and the US hosts three quarters of AI computing capacity against Europe's 5%. AI dependence differs from earlier technologies for three reasons. Data: a model reads a firm's data, so its supplier could learn what an industry knows and compete with it, and nearly half of firms that rejected AI cited data protection. Access: AI will soon screen goods, audit tax returns, dispatch trains and clear payments, so cutting or changing access would hit every sector at once, a leverage no trade partner has held. Frontier: in pharma, finance and defence a small edge in capability brings outsized gains and winner-takes-all dynamics. Europe thus faces a choice between holding back and forgoing growth, or adopting quickly and losing economic freedom. 4. Building sovereign capacity Her answer has three steps. Build far more computing capacity, since Europe's data-centre gap could grow more than sixfold in a decade and the new gigafactories will fill only a fraction. Develop good-enough open models running on European infrastructure, building on Mistral and a San Sebastián firm's compressed model, because the best open models today are Chinese and their terms can change. And secure access to the frontier by being indispensable in the supply chain, as ASML is, while innovating to find the next link, since rivals will try to replicate it. She also warned that a correction in the US AI boom would reach Europe through investment funds exposed to US tech, a task for supervisors, though banks are well capitalised. 5. Capital: more of it, and a different kind All this comes back to capital. Closing the data-centre gap could cost up to 600 billion euros, and the US has drawn on bonds, private credit and securitisation while Europe leans on banks. New models need patient equity; Mistral's record raise last week is one round of the many needed. Europe's households save about 1.4 trillion euros a year, so the savings and investments union is what lets those savings be deployed at home. AI, she argues, can be the project that drives European capital markets forward, as railways did in the US. |
| European Central Bank Wiki12 September 2026 · Christine LagardeWiki (President) Europe seen from Normandy Inflation and price stability · Climate, energy and nature · Trade, fragmentation and geopolitics · Growth, investment and productivity CONTEXT Speech in Épreville-en-Lieuvin, in the Normandy region where the speaker grew up, to a local audience; the ECB keeps prices stable in the euro area and must keep public support for Europe's shared currency. WHY IT MATTERS Connects external shocks to household prices and argues that joining up savings and markets is a priority for Europe. PROBLEMS RAISED | 1. | Europe faces war, an energy shock, tariffs and Middle East conflict. | | 2. | Households feel higher energy and food prices. | | 3. | Fragmented markets lead many founders to leave Europe. |
| SOLUTIONS PROPOSED | 1. | Join up savings and capital markets so the gains of new technologies spread. | | 2. | Reduce national barriers to scaling firms and cross-border investment. | | 3. | Keep inflation at target to protect people's purchasing power. |
|
FULL SUMMARY 1. How Europe helps a region At the Apple Festival in Épreville-en-Lieuvin, Normandy, Christine Lagarde described Europe as built to protect local identity while giving it a larger stage. Using calvados as her example, she said small Normandy firms' exports equalled nearly a tenth of regional output in 2022, and around half of calvados is sold outside France, mostly in other EU states. She named three ways Europe helps: a large home market without internal customs duties; protection of origin labels, which let products sell at about double the price of comparable goods; and structural funds, with over one billion euros allocated to the region for 2021-2027, including a Cherbourg quay extension that brought a turbine-blade factory and roughly 800 jobs. 2. New pressures Yet an open region feels shocks first. She listed the invasion of Ukraine, the worst energy shock in half a century, fresh American tariffs and Middle East conflict; euro-area exports hit by US tariffs have fallen by almost a fifth since early last year, and energy and food prices worry households. Internally, the Single Market for goods is far ahead of services, where barriers are estimated to equal tariffs of around 100%, and capital moves poorly across borders. Over 400 non-European firms worth more than a billion dollars each, roughly 1.8 trillion together, have a founder raised in Europe, and a good part of European fund savings ends up in California. 3. Two priorities First, combine local and European strengths to be less vulnerable. Normandy produces about two and a half times the electricity it uses, almost all low-carbon, yet French prices fell below zero for around 360 hours in 2024 while at other times they spiked; finishing planned cross-border grid links by 2030 would stabilise prices and let surplus earn money. Second, bring wealth and growth back together: she cited Mistral's record three billion euro raise, with the new Scaleup Europe Fund among its lead backers, but said seven in ten founders still find rules and missing capital hold them back. Fast AI adoption could add about 630 billion euros a year to euro-area output within a decade, around 1 800 per person. 4. The ECB's part The ECB will hold inflation to 2% over time so that shocks pass instead of settling in. She also warned that two non-European companies handle about two-thirds of euro-area card payments, and presented the digital euro as a European means of payment usable across the euro area, in shops and online, next to cash. She concluded with Tocqueville on the value of acting together. |
| Bank for International Settlements Wiki11 September 2026 · Pablo Hernández de CosWiki (General Manager) Global economic outlook, AI and innovation Inflation and price stability · Payments, digital money and crypto-assets · Trade, fragmentation and geopolitics · Development and emerging economies CONTEXT Interview with Pablo Hernández de Cos, General Manager of the BIS, with India's Economic Times, conducted by Deepshikha Sikarwar, 11 September 2026. WHY IT MATTERS The BIS General Manager's view of the world economy in one interview: repeated supply shocks, fragmented AI rules and the reach of dollar stablecoins. PROBLEMS RAISED | 1. | Repeated supply shocks lower growth and raise inflation at the same time. | | 2. | Uncoordinated national rules on AI could fragment the system. | | 3. | Dollar stablecoins threaten the monetary sovereignty of emerging economies. |
| SOLUTIONS PROPOSED | 1. | Build geopolitical risks and supply shocks into policy strategies. | | 2. | Coordinate AI regulation globally to limit cross-border risks. | | 3. | Handle stablecoin risks through international cooperation. |
|
FULL SUMMARY 1. A world of repeated supply shocks In an interview during a visit to Mumbai, BIS General Manager Pablo Hernández de Cos said recent central-bank strategy reviews share one conclusion: geopolitical tension and supply disruptions have become more probable. Over six years the world has absorbed the pandemic, the war in Ukraine, tariffs and now conflict in the Middle East. Such shocks push growth down and inflation up, so central banks must look at medium-run effects, stay focused on price stability and watch second-round effects on core inflation and expectations, while recognising they cannot solve everything alone. Growth has so far held up, helped by AI investment and exports. For resilience he sees a three-step approach: inventories in the short run, diversification of suppliers in the medium run, and technology, such as alternative energy sources, in the long run. 2. An AI boom that may not last He warned that AI investment shows signs of becoming unsustainable, for two reasons: a race for market share breeds overinvestment, and spending increasingly relies on debt and leverage, including murky private lending vehicles and circular financing. A bust matters because AI has been a main pillar of recent resilience, supporting investment, wealth-driven consumption (notably in the US) and exports in some Asian economies; a reversal could hit all three, amplified by financial channels. On jobs, AI can complement or replace work depending on the task and sector, so retraining and active labour-market policies are essential, especially in developing economies. 3. Cooperation, cyber and regulation On access to frontier technology, scale economies point to concentration in a few countries and firms, so global cooperation is needed to spread the benefits, and because financial stability is a global public good. AI-enabled cyber capabilities help defenders and attackers alike, and an incident can spread across borders, so coordination is the only effective response. He judged the bigger regulatory danger to be divergence between countries rather than slowness, and held up India's work on fast payments and data privacy as a good example. 4. Stablecoins and tokenisation Stablecoins fall short of what money needs: exchange one-for-one with central-bank money cannot be assured when crises hit, and worries about integrity, fragmentation and interoperability remain. Because they are mostly dollar-based, wide adoption could threaten emerging economies' monetary sovereignty; the answers are international coordination on rules and, at home, good policy that builds trust. He backs two paths: tighter stablecoin regulation, and tokenisation inside the traditional two-tier system, with tokenised bank deposits and central-bank reserves. Project Agorá, on wholesale cross-border payments, now enters its second phase. |
| New Development Bank (BRICS) Wiki10 September 2026 · Dilma RousseffWiki (President) Remarks by President Dilma Rousseff: Launch of the BRICS–NDB Knowledge Portal Development and emerging economies · Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Remarks by the New Development Bank President at the launch of the BRICS–NDB Knowledge Portal, an online knowledge-sharing platform. WHY IT MATTERS Marks a shift in the BRICS bank's role from lender to sharer of know-how and technology among developing countries. PROBLEMS RAISED | 1. | Development banks must do more than provide finance. | | 2. | Knowledge and technology are unevenly shared. | | 3. | Innovation matters more than ever. |
| SOLUTIONS PROPOSED | 1. | Launch the BRICS–NDB Knowledge Portal. | | 2. | Promote capacity building and technology transfer. | | 3. | Exchange successful solutions among developing countries. |
|
|
| Reserve Bank of India Wiki10 September 2026 · Sanjay MalhotraWiki (Governor) Shaping the next decade of finance - technology, trust and innovation Financial stability · Payments, digital money and crypto-assets · Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Keynote address by Sanjay Malhotra, Governor of the Reserve Bank of India, at the Global Fintech Festival 2026, Mumbai, 10 September 2026. WHY IT MATTERS India's central bank sets out its approach to fintech, light rules while small and firmer as activities grow, and announces tokenised bonds settled in central bank money. PROBLEMS RAISED | 1. | Innovation can create systemic risks once it reaches scale. | | 2. | Consumers need protection as digital finance spreads. | | 3. | Many people still lack access to financial services. |
| SOLUTIONS PROPOSED | 1. | Regulate by activity and risk: same activity, same rules. | | 2. | Keep rules light while innovation is small, and step in when it grows. | | 3. | Launch tokenised corporate bonds settled with central bank digital currency. |
|
FULL SUMMARY 1. Potential turned into impact At the Global Fintech Fest, RBI Governor Sanjay Malhotra said that what was once aspiration is now daily reality: roughly 570 million basic bank accounts under the government scheme, hundreds of millions of micro-insurance policies, and about 24 billion UPI payments a month. The real achievement, he said, is that digital finance became ordinary, so even a street flower seller shows a QR code. He credits public-private partnership rather than technology or officials alone. The hardest task remains the last mile: informal-sector savings, micro-insurance, small pensions and small loans for women, farmers and smaller towns, where firms too often chase customers who are already banked. Newer tools, whether AI, quantum computing or tokenisation, are only means to that end. 2. Four ingredients of trust Trust, he said, is a daily working practice, earned one payment at a time. Recalling hundis, the handwritten merchant notes honoured across great distances on reputation alone, he argued that trust once rested on merchants, now rests on institutions and must extend to intelligent systems. His four ingredients: mitigate AI risks such as opacity and bias; treat customer data as a fiduciary duty, following the consent-based design of the Account Aggregator; accept that responsibility grows with size, so firms become too significant to be careless and must invest in resilience and cyber security; and avoid structuring a business around regulatory gaps or scaling first and seeking forgiveness later, since the sandbox exists for early engagement and rules eventually catch up. 3. A global vision India's fintech sector ranks third worldwide by funding, with 2.4 billion dollars raised in 2025 and 30 unicorns. After a decade of building for India, he wants the next to build for the world, exporting solutions for inclusion, affordable payments, digital identity and interoperable public infrastructure, and earning leadership by having others adopt its standards. 4. What the RBI is doing The central bank calls fintech a strategic partner. It runs an on-tap regulatory sandbox, an annual hackathon and a self-regulatory-organisation scheme, recognising United FinTech Forum as the second such body. It is building public infrastructure: the Unified Lending Interface, Account Aggregator, the MuleHunter.ai fraud detector and a proposed Digital Payments Intelligence Platform, plus pilots of programmable CBDC and tokenised certificates of deposit, and it announced tokenised corporate bonds settled in CBDC together with SEBI. Regulation stays activity-based, with the same treatment for the same risk, and light where innovation is young. New AI, model-risk and quantum-resilience work aims to anticipate change. |
| Bank for International Settlements Wiki10 September 2026 · Pablo Hernández de CosWiki (General Manager) Artificial intelligence, growth and financial stability: challenges for central banks Monetary policy and interest rates · Financial stability · Development and emerging economies · Growth, investment and productivity CONTEXT Speech by the BIS General Manager at a large fintech event in India, at the invitation of the Reserve Bank of India. WHY IT MATTERS A reference speech on what AI means for central banks: measurement of the economy, the risk of an investment bust and the gap between rich and poor countries. PROBLEMS RAISED | 1. | Many poorer economies lack the digital infrastructure to benefit from AI. | | 2. | AI makes output and the natural interest rate harder to measure. | | 3. | An AI investment arms race could turn into a bust. |
| SOLUTIONS PROPOSED | 1. | Build on digital public infrastructure, as India has done. | | 2. | Focus AI efforts on areas of comparative advantage instead of duplication. | | 3. | Invest in measurement, judgement and international cooperation. |
|
FULL SUMMARY 1. Demand, investment and trade Speaking at the Global Fintech Fest in Mumbai, BIS General Manager Pablo Hernández de Cos organised his remarks around three questions. AI is already reshaping the global economy. On demand, it has triggered an investment boom in data centres, chips, cloud and hardware, and its optimism keeps financial conditions loose, supporting consumption through wealth effects. The five biggest tech firms alone plan over a trillion dollars of AI spending across 2025-26, and industry expects global AI investment to rise from about 500 billion dollars to 3-4 trillion by 2030, increasingly financed by debt and private credit. Trade is affected too: prices of AI-related goods have risen while other export prices stayed flat, so economies high in the supply chain, such as Taiwan, Korea, Malaysia and Singapore, gain, though narrowly (five Korean firms made 43% of export earnings), while heavy buyers of equipment lose terms of trade. 2. Productivity and jobs On supply, task-level studies show productivity gains of 10 to 65% from generative AI, strongest for less experienced workers, and published estimates centre on roughly half a point a year added to productivity growth, with early evidence that better-prepared economies grew productivity faster. For work, AI both complements and substitutes. Informal workers in developing economies, with least protection and training, are most exposed; displacement so far is limited but emerging in customer support, programming and administration, and nearly 80% of firms discuss automation plans. His lesson is to prepare people through reskilling, not to resist the technology. 3. Divergence between economies Advanced economies are likely to gain more in the short run because finance and professional services weigh more there and AI preparedness is higher. But emerging economies differ widely: China and parts of the Middle East are very well prepared, many low-income countries lag, and India, with its digital public infrastructure, has a real chance to close the gap. AI production is a five-layer chain (chips, cloud, data, foundation models, applications) with high fixed costs and scale economies, favouring a few giants in the US, China, Taiwan, Korea and the Netherlands. Smaller economies face a trade-off between building national capacity for resilience and wasteful duplication; many can focus on local applications, models for local languages and domain data. 4. Central banks and financial stability The mandate is unchanged, but AI makes the economy harder to read, making it harder to pin down how much the economy can produce and where neutral interest rates sit. The BIS sets out three long-run scenarios: a bounded productivity boost, explosive self-improving growth, and a demand bottleneck in which displaced workers, as lost consumers, eventually starve the spending that supports innovation; in the last, the natural rate first rises, then falls below pre-AI levels, with inflation following. Financial-stability worries include cyber risk, which tilts towards attackers, and the investment boom itself: valuations are concentrated, spending exceeds cash flow, and circular financing among chipmakers, cloud firms and AI developers is opaque. An arms race risks over-investment, as in the canal, railway, electrification and dot-com episodes, and households now hold more equity, so a correction could hit consumption harder and spread globally. He does not say a bust is inevitable but urges caution. Benefits will depend on infrastructure, skills, competition, data governance and institutions; for central banks, the premium rises on measurement, judgment and cooperation. |
| 9 September 2026 · Joachim NagelWiki (President) From heritage to renewal - building Europe’s future Climate, energy and nature · Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Evening speech by the Bundesbank President in the Basilica of the Bode-Museum on Berlin's Museum Island. WHY IT MATTERS Given while the ECB Governing Council met in Berlin, this speech sums up the Bundesbank's agenda for European competitiveness, from capital markets to energy grids. PROBLEMS RAISED | 1. | European firms compete from 27 separate markets against the US and China. | | 2. | Promising start-ups must look abroad for funding. | | 3. | Europe lags in AI and depends on others for key technologies. |
| SOLUTIONS PROPOSED | 1. | Build the Savings and Investments Union to channel savings into investment. | | 2. | Invest in data centres, energy grids and cheap, secure electricity. | | 3. | Act at European level wherever scale is decisive. |
|
FULL SUMMARY 1. Europe is not a museum Speaking in the Bode Museum in Berlin, Bundesbank President Joachim Nagel rejected the idea that Europe merely preserves past prosperity while innovation happens elsewhere. The world is harsher and less predictable, competition is fiercer and artificial intelligence is reshaping economies, so competitiveness and sovereignty must be considered together. He notes that Europe depends on non-European providers for chips, computing power and cloud services, and that the most capable models come from the United States and China. 2. Europe's assets and what it needs His view is that Europe can still become a major technological player: it has top universities and AI talent, industrial data and large private savings. But firms cannot race the Americans and Chinese while split across 27 national markets for money, services and workers; Europe must become large in practice. Three things are essential: more venture capital through the Savings and Investments Union, so start-ups need not seek funding abroad; enough computing capacity, meaning data centres, grids and competitively priced power, helped by more cross-border interconnections; and truly integrated markets for digital services and talent so young firms can scale quickly. 3. Act at European level Where scale is decisive, he says, national action falls short and national interests are often better defended by acting jointly, so initiatives should be judged through a European lens. Central bankers can use the Eurosystem's experience to explain what is at stake, and the digital euro is the Eurosystem's contribution to sovereignty. He ends by calling prosperity a launch pad rather than a relic, comparing Europe with a museum that keeps renewing itself. |
| European Central Bank Wiki9 September 2026 · Christine LagardeWiki (President) The choice facing Europeans Growth, investment and productivity · Technology, AI and cyber risk CONTEXT Speech at the Bode Museum in Berlin before German and European guests; the ECB keeps prices stable in the euro area and works in a period of weak growth and strategic tension. WHY IT MATTERS Frames Europe's options as decline, dependence or deeper integration, and argues for the third path. PROBLEMS RAISED | 1. | Europe could drift into graceful decline by relying on others for technology. | | 2. | Middle powers face pressure from larger players. | | 3. | Splintering into 27 national agendas weakens Europe. |
| SOLUTIONS PROPOSED | 1. | Choose to build Europe together and stay united. | | 2. | Strengthen Europe's own capacities rather than import growth. | | 3. | Advance integration, patiently and step by step. |
|
FULL SUMMARY 1. Europe's history of hard choices Speaking at the Bode Museum in Berlin, ECB President Christine Lagarde recalled that post-war Germans and Europeans repeatedly had to pick which relationships to put first, from Adenauer's anchoring in the West to East Germans choosing freedom once the Wall fell. After 1989 the choices seemed to vanish: Europe could source its fuel in Russia, its customers in China and its defence in America simultaneously. She says that era is over, because large powers now use their economic and geopolitical weight for their own benefit. 2. Three pathways Europe, she argues, faces three paths. The first, graceful decline while importing foreign technology to pay for the social model, is a mirage leaving weak growth, an unaffordable welfare state and dependence on suppliers. The second, each country chasing its own interest in trade, industry or energy, is also a mirage: middle powers elsewhere are banding together, and Europe would be throwing away the structures it already has. The third is to choose each other and keep building Europe, accepting slow negotiation and compromise. 3. What that means in practice Single Market strengths are undermined if defence or fragmented, costly energy markets stay weak; acting together where it makes sense brings more sovereignty and faster growth. She points to the savings and investments union, which would channel Europe's savings into needed investment, and to the digital euro, which would protect monetary sovereignty. She calls the choice difficult but not impossible. |
| 8 September 2026 · Andrew BaileyWiki (Governor) Oral evidence: Bank of England Monetary Policy Reports, HC 7 Monetary policy and interest rates · Inflation and price stability · Climate, energy and nature · Labour markets and jobs CONTEXT Hearing of the Governor and members of the Monetary Policy Committee before the House of Commons Treasury Committee on the Bank of England's Monetary Policy Report. WHY IT MATTERS The Governor and rate-setters answer MPs on inflation expectations, food prices and a weakening jobs market: a direct view of how the Bank of England reads the economy. PROBLEMS RAISED | 1. | Household inflation expectations were already high before the conflict. | | 2. | Climate change adds volatility to food prices and supply. | | 3. | The labour market is weakening while households stay cautious about spending. |
| SOLUTIONS PROPOSED | 1. | Watch inflation expectations closely when setting rates. | | 2. | Assess whether price pressures are becoming chronic. | | 3. | Address global imbalances with action by China, Europe and the US together. |
|
FULL SUMMARY 1. Energy, the Gulf conflict and the refining wedge At the Treasury Committee's hearing on the Bank of England's Monetary Policy Reports, Governor Andrew Bailey said the conflict in the Gulf is still driving high and volatile energy prices, with most of the financial-market volatility traceable to it. The Strait of Hormuz remains largely shut; pipelines are being used more, but even they are exposed after Houthi attacks in the Red Sea area, and emergency stock releases that have helped can only run until about November. Oil production has risen somewhat elsewhere. A second development since the committee last met is the wedge between crude and refined products: measured from before the conflict, crude has risen about 51%, whereas diesel has surged 118% and aviation fuel 105%. Part of that gap has nothing to do with Hormuz, because Ukrainian strikes have cut Russian refining capacity, perhaps by around 60%, and some US refineries are running hot or closing, so even a settlement in the strait would leave the refining squeeze in place. Asked whether overworked refineries could run into maintenance problems, he agreed this is a concern, above all in the United States, where facilities are working at high rates while a couple of planned closures also tighten capacity, which could keep the wedge elevated for some time. Deputy Governor Dave Ramsden added that maintenance cannot be postponed indefinitely and that attacks on installations, such as a Saudi refinery hit by the Houthis, make crude and product prices harder to predict the longer the war lasts. 2. Why members voted as they did Alan Taylor described a very uncertain environment: earlier this year core and headline inflation were falling towards target, and without energy effects April's rate would have matched it, but oil has since moved in a higher corridor of 70 to 100 dollars, and gas, central to British electricity prices, is edging up ahead of a delicate winter. In his view, the outcome depends on which comes first: the expiry of stopgap measures or the adjustment of firms and households on both the demand and supply side. Megan Greene, who voted for a rise, argued that after six months of volatile energy costs the risk of second-round effects justifies a risk-management approach: if the Bank tightens and the effects do not appear, it can course-correct cheaply, whereas if it waits and they do, inflation is hard to get back under control. Conclusive evidence on second-round effects may not arrive until next year, and policy must act on lags. Ramsden, who voted to hold, saw the domestic picture as benign, since private-sector regular pay grew 2.8% in the second quarter against 3.2% expected before the conflict, while seeing global risks, from energy, extreme weather, drought and AI, as mostly on the upside. He still counts unchanged rates as restrictive, as he had expected cuts in spring. Taylor made a similar case: domestic inflation has been coming in below forecast for 12 to 18 months, and by not cutting as expected the Bank has actively kept policy tighter than peers, which is a form of insurance. Greene admitted she has no special insight into how the war will end, which is exactly why she prefers to minimise potential losses, and Taylor said the staff's monitoring will concentrate on wages and on how far energy costs spill into other sectors, compared with earlier energy shocks, adding that he regards the unchanged rate as an active decision rather than inaction. Greene differs mainly in her starting point, noting that agents report slightly lower pay settlements this year but that, with inflation about to accelerate, next year's may not be much lower, which would suggest wage disinflation is stalling, citing weaker wage disinflation, household inflation expectations already at the top of their historical range, and thresholds above which households and firms pay more attention to price rises. 3. Conditional statements, the market curve and mortgage rates Asked how Bailey could say the market curve is consistent with the Bank's reading while also warning against assuming a hike, he explained that the first statement is conditional: risks from energy prices and from second-round effects lean to the upside, and the gap between the curve and what market participants expect from the Bank reflects a risk premium. The second pushed back on an unconditional reading that the Bank has a secret plan to raise rates. He sided with the new Fed Chair Kevin Warsh that forward guidance, which tries to turn conditional statements into unconditional ones, is dangerous, though he is sometimes frustrated that his conditional remarks are heard as promises. On financial conditions, he noted that UK mortgage rates are about 75 basis points above their level when the conflict began, the largest rise in the G7 with the possible exception of Japan, which is a genuine tightening that the Bank takes into account, but not a case of letting markets do its work: both markets and the Bank are responding to the same upside risks. Pressed on whether this market-driven tightening can substitute for a rate rise indefinitely, he said financial conditions are simply another piece of data the committee weighs, and that the effect on families is taken into account. Ramsden explained that the monitoring framework for second-round effects relies on the decision-maker panel and other forward-looking surveys, with the main difficulty being wages, because most settlements happen around the turn of the year and the conflict began after the 2026 round was done. 4. Communications after the Bernanke review On implementing the Bernanke review, Bailey cited two linked changes to communications: individual paragraphs in the minutes now show each member's reasoning and vote, while the group's statement now reports what the majority decided and why, instead of the earlier compromise wording that everyone could shelter under and that critics called contorted. Scenarios are also a product of the review, and the review has an iceberg below the surface in data, models, tools and use of AI. Some outsiders find nine separate explanations confusing, but he reports positive feedback overall and a clearer picture of where each member stands and why. Asked whether the three-scenario approach without a stated central forecast helps, Taylor replied that this was specific to the period of grave uncertainty right after the conflict began, when a single central path might have misled, and the Bank has since returned to a baseline. Taylor said there are three balances to strike: the quantity and quality of information (too much is like too much salt), a clear central view without unconditional guidance, and individual accountability alongside a strong collective message; communicating the reaction function through scenarios builds credibility, and the aim is to subtract noise, not add it. Ramsden recalled that scenarios replaced a single forecast in April because uncertainty was so great, before the July report returned to a baseline with adverse and benign scenarios. Ramsden judged that market volatility after both the April and July publications was limited, a sign the message about policy and its risks got through, and Taylor said the central forecast remains a baseline that expresses a view while the scenarios convey how the committee would react to other developments. Bailey and Greene noted that the Bank's nine-member, individually accountable structure, and the unusual practice of several members appearing before a legislature, makes it fundamentally different from the Fed. 5. Food, El Niño and chips In response to a rural member's account of early lamb sales and pasture shortages, Bailey said the Bank's agents pick up similar signals: yields of winter wheat, spring barley and oats are already down and some prices are rising. An El Niño is building, which historically affects rice, coffee, cocoa and palm oil. Food inflation has so far come in below expectations, at 1.7% in July, but the Bank expects it to rise to about 3.5% by year-end and sees risks as skewed upward; trade bodies have trimmed earlier forecasts of 6-7%. Ramsden said the lesson of 2022 is to watch fertiliser and input costs for next year, and that central bankers from nations already feeling the El Niño reported food price effects at the Basel meetings, and those will reach Britain with a lag. Bailey was cautious about linking El Niño to climate change, while accepting global food prices are more volatile. Greene made the point that frequent shocks mean volatility rather than ever-rising inflation, and she added that no one knows how supply shocks interact, such as AI chip demand, the Iran war and others. Staff modelling suggests chip price pressure could add about 0.1 percentage point to consumer prices. Ramsden added that food is a necessity, so what matters is whether shocks are global and whether consumers can substitute, for example away from dear meat, and that with few favourable supply shocks lately, prices are more likely to ratchet up than down. 6. Quantitative tightening, the 1844 Act and reserves Ramsden said estimates of QT's effect on borrowing costs have risen from 15-25 basis points to 20-30, a small share, roughly a sixth to a tenth, of the rise in term premia, after a reduction of about 400 billion pounds that took the Bank's holdings below half a trillion, with QT meant to stay gradual, predictable and in the background while Bank Rate remains the primary tool. He defended QE as a tool at the zero lower bound and in the pandemic, though a third round of 150 billion over twelve months should have had a review point, and he voted against completing it as inflation worries grew. On the fiscal losses from QT, Bailey explained that under the 1844 Bank Charter Act the note-issue department's profit, the seigniorage, goes straight to the Treasury, whereas the Fed and the ECB keep everything on one balance sheet, offset losses against seigniorage and book a negative asset. The UK approach is more transparent but makes the losses visible, though in economic terms it makes no difference to the taxpayer, and the Government also gained from issuing long debt cheaply in the zero-rate period, a benefit the Bank now publishes an attempt to net against the losses, which comes out roughly flat. Most reserves, he added, are held for financial-stability reasons. He would not comment on fiscal policy or proposals to tax banks, but argued that paying interest on reserves is how rate decisions are implemented and that stopping it would cut bank margins and most likely be passed on to customers. 7. The economy, labour market, AI and young people Asked about recession risk, Bailey said no scenario had one, even though the OECD has marked Britain down more than any other G20 economy to 0.7% growth for 2026; activity is weak by historical standards but resilient, balance sheets are sound, household saving has been high, and data since the report have come in somewhat stronger. Second-quarter growth was 0.4%, above expectations, consumer confidence is the highest since August 2024, and the June GDP figures should support the third quarter, though Taylor and others noted a recurring pattern of stronger first halves that the statistics office attributes in part to changed seasonality. Real post-tax labour income grew 3.3% on average from 1998 to 2007 but only 1.5% since the financial crisis, so productivity remains the central challenge. Asked to separate external shocks from the effect of higher employer payroll taxes on hiring, Bailey said softer second-round effects imply that firms are absorbing some costs in margins, so hiring is lower and the labour market is softening, with youth unemployment concerning; Ramsden stressed that there is less firing too, giving low turnover. Greene said early data show fewer vacancies in AI-exposed sectors, but the low-hire, low-fire dynamic matters more for young people, and much of what firms call AI is really automation. Bailey cited a four-part framework of jobs destroyed, created, augmented or reduced in demand, and warned that long spells outside work scar future prospects, so skills matter, with a tension between universities worried students will only use AI and employers wanting AI users. Taylor put the slowdown in long-run context: advanced-economy growth has decelerated for fifty years, so falling to zero from 1% is easier than from 3%, and he warned against overstating resilience, since without the conflict hiring and optimism would probably be stronger and the damage to long-term supply potential lower. Bailey said recent productivity gains are mostly in some service sectors rather than AI-heavy ones and could simply reflect fewer workers. Ramsden expects a premium on technological literacy. Greene also called UK consumers a puzzle: they behave like euro-area ones, saving heavily, saying it is a bad time for big purchases and yet not fearing for their jobs, which could reflect precautionary hoarding after inflation or mortgage resets and would imply opposite policies. 8. Global imbalances, trade and the Bank's own house On imbalances, Bailey said it takes more than one country to create them and some are healthy, but China's very large surplus, industrial policy, capital controls and low household consumption, alongside the US fiscal deficit, make a better debate necessary, which Britain wants to promote when it holds the G20 presidency next year. Ramsden pointed out that Britain is among the world's largest services exporters, with a comparative advantage in finance and professional services, as the global trading system intends. Britain runs a goods shortfall against China, partly offset by services, though the services surplus, which includes education, is smaller, and he sees AI and robotics as the next general-purpose technology that the UK must be part of. Greene noted that imbalances reflect savings and investment everywhere, so China, Europe and the US would all have to adjust. Taylor said trade diversion is a slow burn, citing Chinese electric vehicles and overbuilding that will find other markets, and Bailey agreed to write with an estimate of tariffs' effect on UK inflation, which staff think is smaller than first feared. On staffing, just over 400 people are leaving the Bank under a mutually agreed resignation scheme out of about 700 applicants, to shift spending towards systems and data, a need sharpened by frontier AI. On new banknotes, whose reverse will carry wildlife chosen by almost half a million people from a curated panel, there is no date and Bailey said it will not happen in his term. |
| 4 September 2026 · Andrew BaileyWiki (Governor) The institutional form of independent central banks - from history to contemporary challenges Financial stability · Labour markets and jobs CONTEXT Lecture by the Governor of the Bank of England on the history and present-day challenges of central bank independence. WHY IT MATTERS Explains why independence exists and how it should be exercised, at a time when it is openly questioned. PROBLEMS RAISED | 1. | The authority of independent central banks is being questioned. | | 2. | Independence is often seen as a narrow technical matter. | | 3. | Central bank decisions deeply affect jobs, savings and financial stability. |
| SOLUTIONS PROPOSED | 1. | Ground independence in history and in its democratic purpose. | | 2. | Treat central banks as durable institutions that solve collective problems. | | 3. | Be clear about how authority is exercised and conflicts managed. |
|
FULL SUMMARY 1. The question of legitimacy Speaking at an LSE conference, the Governor of the Bank of England examined independent central banks as institutions. He recalled that in 1780 a young Alexander Hamilton admired how the Bank of England combined public authority with private credit. Since central banks shape borrowing costs, savings, jobs and financial stability, critics ask why unelected bodies should hold such power: some say they serve financial interests, others that they ignore citizens' wishes. He set out to answer by tracing the ideas behind them. 2. Two intellectual traditions Economists usually justify independence by credibility: governments are tempted by short-term monetary choices and tend to neglect financial stability until a crisis is near. Bailey went further back. Montesquieu wanted intermediate bodies, such as courts and parliaments, to restrain arbitrary power, though their authority grew from long-standing roots. A second line of English thought moved money away from the sovereign's control: Hobbes saw monetary power as part of sovereignty, while Locke, in the coinage disputes of the 1690s, argued that changing money's value at will destroyed trust and trade, and Hume presented stable money and credit as foundations of commercial prosperity. Monetary stability thus became a public good. 3. The early Bank of England The Bank was founded in 1694 to support expanding commerce and to fund war with France. It began as a deal between the state and a small circle of wealthy financiers and was deeply involved in politics; writers at the time feared that public debt would give financiers power without legitimacy. Central banking therefore evolved slowly, and its origins resemble Mancur Olson's organised interest groups more than a neutral public institution. 4. Public good, not group interest Modern central banks combine both traditions: they limit the misuse of power over money and protect a good shared by all. Drawing on Brian Barry, Bailey distinguished competing private interests, which democracy arbitrates, from goods that matter to everyone, such as the value of money. Interest rates and financial rules do affect groups differently, but their purpose is to preserve conditions for lasting prosperity. Lacking deep social roots, a central bank must avoid being captured by any sector or movement. Its legitimacy comes from Parliament, which sets its goals and powers and can change them. 5. Today's challenges Trust in public bodies is falling. Critics say central banks are too close to finance, while banks complain that regulation has gone too far; criticism from both sides does not prove the bank right, but shows that independence means resisting organised interests. Populism is a second threat: by claiming to embody the whole people, it erases the line between public interest and public good and treats independent bodies as obstacles. Central banks must therefore explain their choices, engage with the public and answer to elected representatives, in Britain the Treasury Committee. 6. Conclusion Scrutiny is healthy. Prosperity depends on confidence that money keeps its value and the financial system holds. Independence means protection from short-term political pressure inside a democratic framework, resting on delegation and accountability, which should be strengthened through transparency and openness. Households, firms and markets all plan on the basis of stable money, and such trust takes generations to build but can be lost quickly, which is why he argued that the foundations of independence should be reinforced rather than weakened. |
| 3 September 2026 · Vitai RatanakornWiki (Governor) Thailand's new horizons - empowering people, building resilience Financial stability · Payments, digital money and crypto-assets · Climate, energy and nature · Trade, fragmentation and geopolitics CONTEXT Address to the Bangkok Business Summit 2026, invited by Thailand's joint commerce, industry and banking committee; the Bank of Thailand keeps prices and finance stable and faces slow growth and high household debt. WHY IT MATTERS Shows Thailand's slowing post-crisis growth and a policy agenda on resilience, climate adaptation and tighter anti-scam measures. PROBLEMS RAISED | 1. | Each successive crisis has left Thai growth on a lower path. | | 2. | Climate risks and fragmentation hit vulnerable people and small businesses hardest. | | 3. | Digital finance and AI bring scams and illicit cash flows. |
| SOLUTIONS PROPOSED | 1. | Build the skills and capabilities of people and small firms to adapt. | | 2. | Direct more investment and finance towards climate adaptation. | | 3. | Tighten scam, money-tracing and cash-transaction safeguards so they keep pace with innovation. |
|
FULL SUMMARY 1. Shocks and weaker growth Addressing the Bangkok Business Summit, Bank of Thailand Governor Vitai Ratanakorn noted that shocks now arrive faster, and each has left Thailand on a lower growth path: average growth fell from 5.3% after 1997 to 3.7% after 2008 and 2.4% after the pandemic. Ahead of the IMF-World Bank meetings in Bangkok, he framed the theme of new horizons, empowering people and building resilience, around four pillars: digital and AI transformation, resilience in a fragmented world, climate-adaptation finance, and demographic change and the longevity economy. 2. The other three pillars Thailand can be a trusted hub: though not the cheapest location, it offers stability, and over five years foreign direct investment into the country rose 20.9% while global flows fell 4.2%. Small firms need help adjusting. On climate, the central bank's transition financing and Thailand Taxonomy have supported over 750 businesses and mobilised more than 210 billion baht, with the taxonomy covering six sectors that account for 95% of emissions. Ageing opens opportunities in healthcare and wellness. 3. Digital finance and fraud Thailand's free instant-payment system PromptPay has 83 million accounts and handled 2.51 billion transfers in July alone, and the Paotang app built on it reaches over 40 million users. But scams are growing: Asia suffered close to 66% of the world's scam losses in 2024, Thai fraud cost over 43 billion baht (about 0.2% of GDP), and attacks on banks rose roughly 45% in 2025. With the IMF and World Bank, Thailand drafted the Bangkok Blueprint, twelve considerations for fraud-resilient finance. Security standards cut money-draining apps to zero, and later measures against authorised push-payment fraud (tougher scam-account rules, money tracing, daily transfer caps, shared-responsibility guidelines) cut such losses almost 80% from the 2024 peak. 4. Cutting off illicit money Since fraud proceeds exit through cash, gold, foreign exchange and stablecoins, the bank limited large cash withdrawals (down 52%), tightened online gold reporting (large withdrawals down 70%), strengthened oversight of currency exchangers and, with the SEC, tightened rules for digital-asset trading. A new framework of commitments across banks, e-payment firms, lenders and money changers will be reaffirmed next week, because a secure system is a strategic asset. |
| 2 September 2026 · Hyun Song ShinWiki (Governor) Opening address - Bank of Korea-Centre for Economic Policy Research-Organisation for Economic Co-operation and Development Conference Public finances and debt · Development and emerging economies · Technology, AI and cyber risk CONTEXT Recorded opening address by the Bank of Korea Governor to a conference on the economics of ageing and longevity, co-organised with the CEPR and the OECD. WHY IT MATTERS Korea's central bank chief puts ageing and the low birth rate at the centre of economic policy, warning that AI is not a substitute for structural reform. PROBLEMS RAISED | 1. | Korea's population is ageing fast and its birth rate is very low. | | 2. | Ageing economies must make large fiscal adjustments in little time. | | 3. | AI will not solve structural problems on its own. |
| SOLUTIONS PROPOSED | 1. | Invest in research on long-term structural issues. | | 2. | Prepare early for demographic change, which is predictable. | | 3. | Use Korea's AI and semiconductor strength as an opportunity. |
|
|
| 2 September 2026 · Tiff MacklemWiki (Governor) Monetary Policy Decision Monetary policy and interest rates · Inflation and price stability · Climate, energy and nature · Trade, fragmentation and geopolitics CONTEXT Opening statement by Tiff Macklem, Governor of the Bank of Canada and Carolyn Rogers, Senior Deputy Governor of the Bank of Canada, at the press conference following the monetary policy decision, Ottawa, Ontario, 2 September 2026. WHY IT MATTERS The Bank of Canada's explanation of its September decision, with new US tariffs and high energy prices as the two main risks. PROBLEMS RAISED | 1. | New US tariffs threaten Canada's economic rebound. | | 2. | The Middle East conflict keeps energy prices high for longer. | | 3. | High oil prices could turn into persistent inflation. |
| SOLUTIONS PROPOSED | 1. | Monitor whether the economic rebound is sustainable. | | 2. | Watch the inflation outlook closely, especially energy spillovers. | | 3. | Stand ready to adjust monetary policy as needed. |
|
|
| European Securities and Markets Authority Wiki1 September 2026 · Verena RossWiki (Chair) Verena Ross' keynote speech at the European Capital Markets Dialogue, 31 August 2026 Monetary policy and interest rates · Banking regulation and supervision · Trade, fragmentation and geopolitics CONTEXT Keynote by the ESMA Chair at the European Capital Markets Dialogue in Dubrovnik, hosted by the Croatian and Luxembourg market supervisors. WHY IT MATTERS The ESMA Chair draws a line between smart simplification and deregulation that would weaken investor protection. PROBLEMS RAISED | 1. | Indiscriminate deregulation could weaken investor protection. | | 2. | Proportionality can slide into fragmentation. | | 3. | Risks increasingly cross national borders. |
| SOLUTIONS PROPOSED | 1. | Simplify through smart, risk-focused supervision. | | 2. | Use peer reviews and common supervisory actions across Europe. | | 3. | Reduce reporting burdens while improving risk detection. |
|
FULL SUMMARY 1. Simplification built on confidence Speaking in Dubrovnik at a conference hosted by Croatia's HANFA and Luxembourg's CSSF, ESMA Chair Verena Ross, whose term is ending, echoed the Lamfalussy report's call twenty-five years ago for agile regulation. Beyond the question of courage to simplify, she asked whether policymakers have confidence that simpler rules can still work. Complexity can give a false sense of control and, in an unpredictable world, make the system clumsy and less competitive. She rejected indiscriminate deregulation that would weaken investor protection or stability; the aim is a strong supervisory framework, using quality data, convergence and enforcement, that reaches its goals without ever more detailed rules. 2. The cost of fragmentation She warned that proportionality must not turn into fragmentation: each exemption or national flexibility may make sense locally, but the accumulated differences impose hidden costs on the whole market, making it harder for firms to expand, investors to find opportunities and Europe to compete. A stronger European dimension of supervision should be seen as an opportunity; it will not erase differences between markets but can make them less of a barrier. 3. A joint undertaking and the 2030 picture Whatever negotiators decide on the market integration and supervision package, she says supervision stays a partnership that combines national expertise with a European view, built through peer reviews, joint actions, colleges and shared methods. For 2030 she pictures supervision more integrated yet rooted in national markets, digital and data-driven, focused on outcomes, with fewer box-ticking duties, lighter reporting, predictable expectations for cross-border firms and investors confident to take part, moving Europe nearer a genuine single market for capital. |
|
Dark Majestic is independent and is not affiliated with any of the institutions or people listed. Summaries are our own reading of public speeches; they are not official texts and not investment advice. Nothing here is investment advice. Each speech links to the official page of the institution.
Full database and analysis: darkmajestic.org. You receive this newsletter as a thank-you for supporting Dark Majestic on Ko-fi. Unsubscribe.
|
|